Blog > Assumable VA Loans on the Gulf Coast: When They're Worth It and When They Aren't
Assumable VA Loans on the Gulf Coast: When They're Worth It and When They Aren't
by
Assumable VA Loans on the Gulf Coast: When They're Worth It and When They Aren't
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Keesler AFB PCS guide.
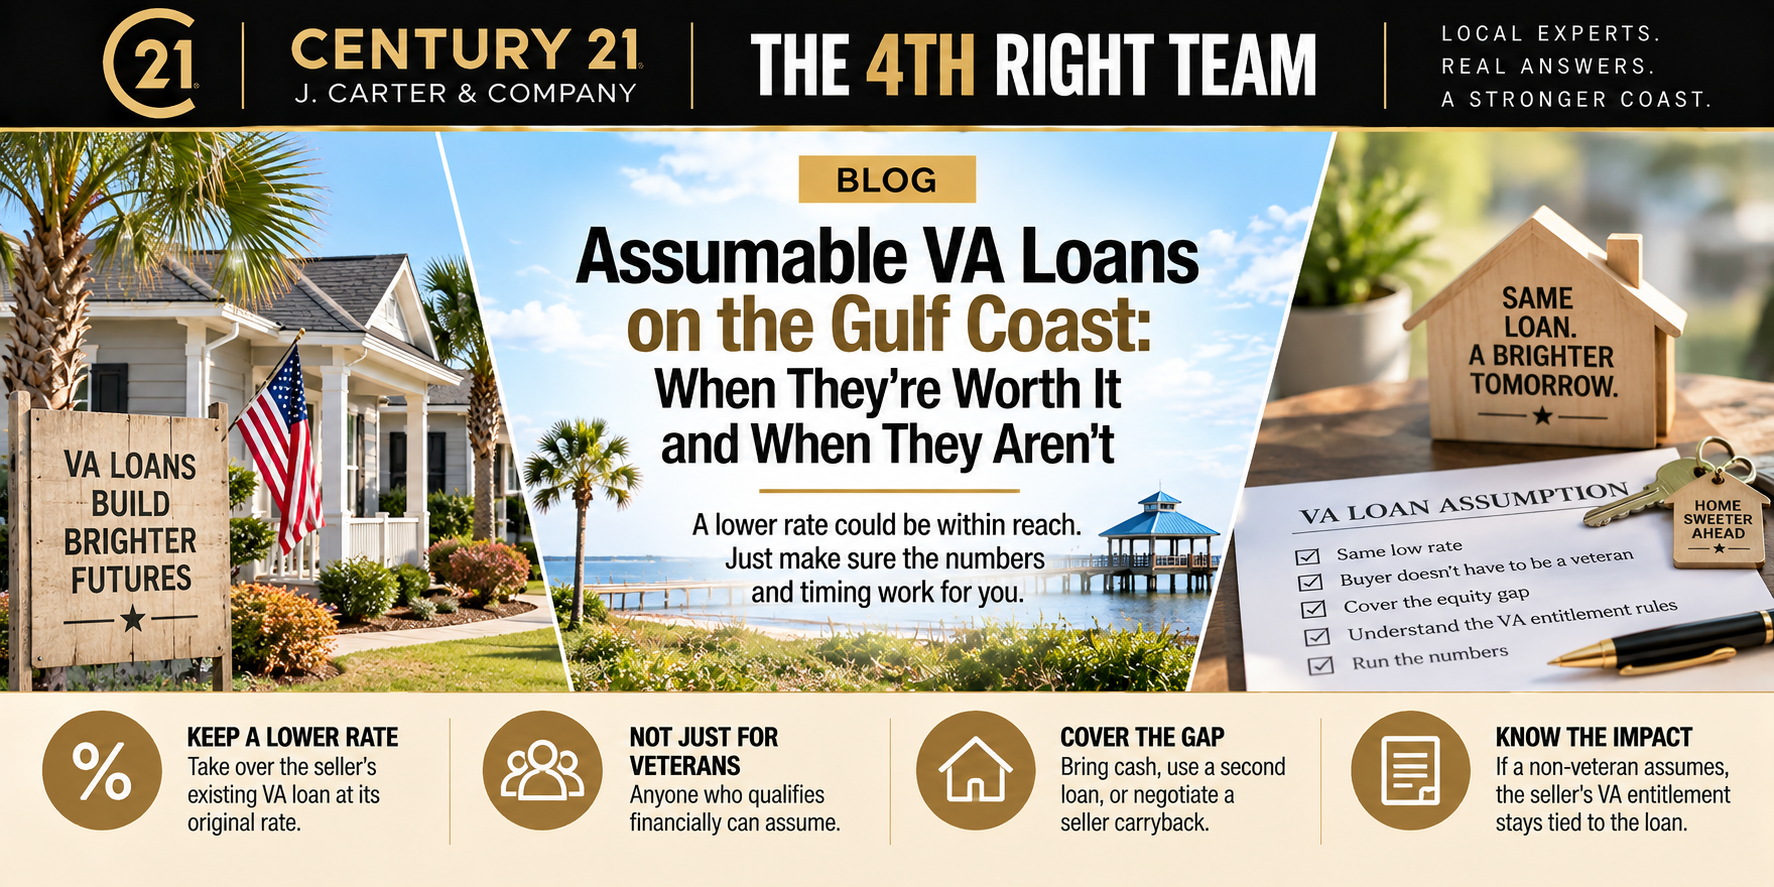
Quick Answer: VA loans are assumable, which means a buyer can take over a seller's existing mortgage at its original rate. With market rates near 6.5% and plenty of Coast homes carrying 2020 and 2021 VA loans in the 2.5 to 3.5 percent range, that's real money. The buyer doesn't have to be a veteran. Anyone who qualifies financially can assume. The catch cuts both ways. The buyer has to cover the gap between the sale price and the loan balance, usually in cash. And if a non-veteran assumes, the seller's VA entitlement stays tied to that loan until it's paid off, which can block them from using their VA benefit at the next duty station. On the Coast, where prices are lower than most military markets, the gap is often small enough to make this work.
How does a VA loan assumption actually work?
The buyer steps into the existing loan. Same rate, same remaining term, same payment schedule. If a seller has a 2.75% mortgage with 25 years left on it, the buyer inherits exactly that.
The buyer still has to qualify. The servicer underwrites credit, income, debt-to-income, and residual income the same way a lender would on a new loan. You don't get to skip that part.
Two things make assumptions cheaper than a new loan. The funding fee is 0.5% of the balance being assumed, versus 1.25% to 3.3% on a new VA purchase loan. And a standard assumption typically doesn't require a new appraisal, which saves time and money. There's no mortgage insurance either, same as any VA loan.
That 0.5% fee has to be paid in cash at closing and can't be rolled into the loan. Veterans exempt from the VA funding fee because of a service-connected disability rating are exempt from the assumption fee too. There's also a servicer processing fee, which VA circulars cap, plus normal settlement and recording charges.
Do you have to be a veteran to assume a VA loan?
No. This surprises almost everybody, and it's the piece that changes the math for sellers.
Assumption eligibility is about your financial profile, not your service record. A civilian with good credit and stable income can assume a VA loan. No DD-214 required. That means a Coast seller sitting on a 2.75% VA mortgage isn't marketing to veterans only. They're marketing to the whole buyer pool with an interest rate nobody else on the street can offer.
In a market where buyers are waiting on rates that keep not dropping, that's a real advantage. It's the closest thing to a free upgrade a listing can have.
What do the numbers look like on the Coast?
Run it with real Coast figures instead of California ones, because the answer is different.
Say a veteran bought in Gulfport in 2021 for $210,000 with nothing down at 2.75%. Five years in, the balance is around $185,800, and the principal and interest payment is about $857 a month. Gulfport's median sold price was $217,900 over the six months ending September 6, 2026, per Resideline.
So the equity gap is roughly $32,000. That's what the buyer has to bring beyond the assumed balance.
Now compare payments. That same $217,900 financed new at the September 10, 2026 national average 30-year VA rate of 6.47% runs about $1,373 a month in principal and interest. The assumed loan runs $857. That's a difference of roughly $516 every month, and the buyer is five years into the amortization instead of starting over.
Put that against a market like Hampton Roads or San Diego, where the same 2021 loan sits under a house that's appreciated $200,000, and you see why this works better here. Our lower prices mean smaller gaps. That's the local advantage, and almost nobody writes about it. You can see the broader Gulfport and Biloxi price picture if you want to test it against a different starting point, or run your own numbers on our payment calculator.
How do you cover the gap?
Thirty-two thousand dollars is still thirty-two thousand dollars, and that's the most common reason assumption deals fall apart.
There are three ways to bridge it. Cash, which is cleanest. Secondary financing, meaning a second lien that sits behind the VA first through subordination, which VA allows when it's processed correctly. Or a seller carryback, which is the same idea with the seller holding the note.
If you go the second lien route, understand that the second's payment gets counted in your debt-to-income and residual income tests. You can't borrow your way past qualifying. And the buyer can't take cash back out of the transaction.
If you're pulling together the gap money, the same conversations apply as any other down payment. Some buyers look at a 401(k) withdrawal. Some look at down payment assistance programs, though eligibility for assumption use varies and you'd need to confirm it. Talk to a lender early, because this is not a standard file.
What happens to the seller's VA entitlement?
This is the part that should decide whether a seller does this at all.
When a buyer assumes a VA loan, the seller's entitlement does not automatically come back. If the buyer is a veteran who completes a Substitution of Entitlement at closing, the seller's entitlement is restored. If the buyer is a civilian, the seller's entitlement stays tied to that property until the loan is paid off.
Think about what that means for somebody PCSing out of Keesler or leaving NCBC Gulfport. You sell your Biloxi house to a civilian through an assumption. You get a fast sale and a happy buyer. Then you land at your next base and find out you can't buy with zero down anymore, because your entitlement is still attached to a house in Mississippi.
That's not a reason to never do it. Partial entitlement may still leave you room, depending on your loan amount and the county limits at your next station. But it's a calculation you run before you sign the contract, not after. If you're a service member who expects to buy again within a few years, an assumption by a civilian is a much bigger decision than it looks like.
The second seller trap is the Release of Liability. It is not automatic. If you don't formally request and receive one through the servicer, you can stay personally liable for that mortgage after you've moved on. Sellers have found this out months later, when the full balance was still showing on their credit. Verbal reassurance from anybody, including the buyer, is worth nothing here. Get it in writing.
How long does a VA assumption take?
Longer than a normal closing. Current guidance points to 45 days as a floor, with 45 to 75 days more realistic depending on the servicer. Underwriting the buyer runs two to four weeks on its own, longer if the file needs manual underwriting. Adding a release of liability or an entitlement substitution adds processing time.
Worth knowing if your servicer drags: VA circulars describe assumptions as a fundamental feature of VA-guaranteed loans, and servicers can't discourage or refuse to process a qualified assumption. If yours stalls, that's escalation material for the VA Regional Loan Center.
For a military seller working against report dates, that timeline is the practical constraint. Build it into your plan the same way you'd think through selling first or buying first. And none of this changes the Coast basics. You still need to quote insurance on the address before you write.
By the Numbers
0.5%: VA funding fee on an assumption, paid in cash, not financeable
1.25% to 3.3%: funding fee range on a new VA purchase loan, for comparison
6.47%: national average 30-year VA rate, September 10, 2026
$217,900: Gulfport median sold price, six months ending September 6, 2026, per Resideline
~$185,800: illustrative remaining balance on a $210,000 loan at 2.75% after 5 years
~$32,000: illustrative equity gap in that scenario
~$516: illustrative monthly principal and interest savings versus financing new at 6.47%
45 to 75 days: realistic assumption processing window
0: military service required for a buyer to assume a VA loan
0: mortgage insurance on a VA loan, before or after assumption
The Bottom Line
For a buyer with cash for the gap, assuming a low-rate VA loan on the Coast is one of the best deals available right now, and you don't have to have served to get it. Our prices keep the gap small enough that ordinary buyers can actually clear it, which isn't true in most military markets.
For a seller, it's a real marketing advantage and a real risk at the same time. The rate attracts buyers. The entitlement question can cost you your next zero-down purchase. Run that math before you list, not after you're under contract.
And whoever you are in the deal, get the Release of Liability in writing and confirm the actual balance and rate with the servicer. Don't take the payoff number off an old statement.
Thinking about listing and wondering whether your rate is worth marketing? Start with a home value estimate, and our page on the selling process covers the rest. If you're buying, the buyer's guide walks the timeline, you can browse what's listed in Biloxi, and a local agent can help you spot which listings are carrying assumable paper.
Frequently Asked Questions
Do I have to be a veteran to assume a VA loan?
No. Assumption eligibility is based on your financial qualifications, not your military service. A civilian with adequate credit, income, and debt-to-income ratios can assume a VA loan. Only a veteran buyer, however, can substitute entitlement and free up the seller's.
What does a VA loan assumption cost?
The buyer pays a VA funding fee of 0.5% of the balance being assumed, in cash at closing, since it can't be financed. There's also a servicer processing fee capped by VA circular, a credit report cost, and normal settlement and recording charges. Veterans exempt from the VA funding fee due to a service-connected disability are exempt from the assumption fee.
What happens to the seller's VA entitlement?
If the buyer is a veteran who completes a Substitution of Entitlement at closing, the seller's entitlement is restored. If the buyer is a civilian, the seller's entitlement stays tied to that loan until it's paid off or refinanced out of the VA program. That can limit the seller's ability to buy again with zero down.
Is the seller released from the mortgage automatically?
No. A Release of Liability has to be formally requested and obtained through the servicer. Without it, the seller can remain personally liable if the buyer defaults later, and the balance can continue showing on their credit.
How does the buyer cover the difference between the price and the loan balance?
With cash, with secondary financing through a second lien subordinated behind the VA first, or with a seller carryback. VA permits secondary financing when it's processed correctly, but the second lien's payment counts in the buyer's debt-to-income and residual income calculations, and the buyer can't receive cash back at closing.
How long does a VA assumption take?
Longer than a typical purchase. Guidance points to 45 days as a minimum, with 45 to 75 days more realistic. Buyer underwriting alone takes two to four weeks, and adding a release of liability or entitlement substitution extends it further.
Does an assumption require a new appraisal?
Generally no. Standard VA assumptions typically skip the formal appraisal step, which saves both time and cost compared with a new purchase loan. The servicer may still verify property condition.
Sources
U.S. Department of Veterans Affairs, VA home loan program: https://www.va.gov/housing-assistance/home-loans/
VA funding fee schedule, including the 0.5% assumption rate: https://www.va.gov/housing-assistance/home-loans/funding-fee-and-closing-costs/
VA Circulars on loan assumption processing and servicer obligations: https://www.benefits.va.gov/homeloans/resources_circulars.asp
VA Loan Network, VA loan assumption guide including processing fee limits and timelines, July 2026: https://valoannetwork.com/va-loans/va-loan-assumption/
VA Loan Network, assumptions and secondary financing, May 2026: https://valoannetwork.com/va-assumptions-secondary-financing/
USMilitary.org, VA loan assumption process and entitlement effects, March 2026: https://usmilitary.org/assuming-a-va-loan/
Optimal Blue 30-year VA average rate, September 10, 2026, via CNBC Select: https://www.cnbc.com/select/what-are-va-loan-rates-today-sept-10-2026/
Resideline, Gulfport MS market data, updated September 6, 2026: https://resideline.com/blog/gulfport-ms-housing-market
Keep reading: Using a VA Loan to Buy Near Keesler or NCBC Gulfport and Keesler AFB PCS Guide: Buying a Home Near Biloxi in 2026
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He works with buyers and sellers across the Mississippi Gulf Coast, from Bay St. Louis to Pascagoula and north of I-10.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!