Blog > Coast Buyers: Get the Insurance Quote Before the Offer
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Mississippi Gulf Coast home insurance guide.
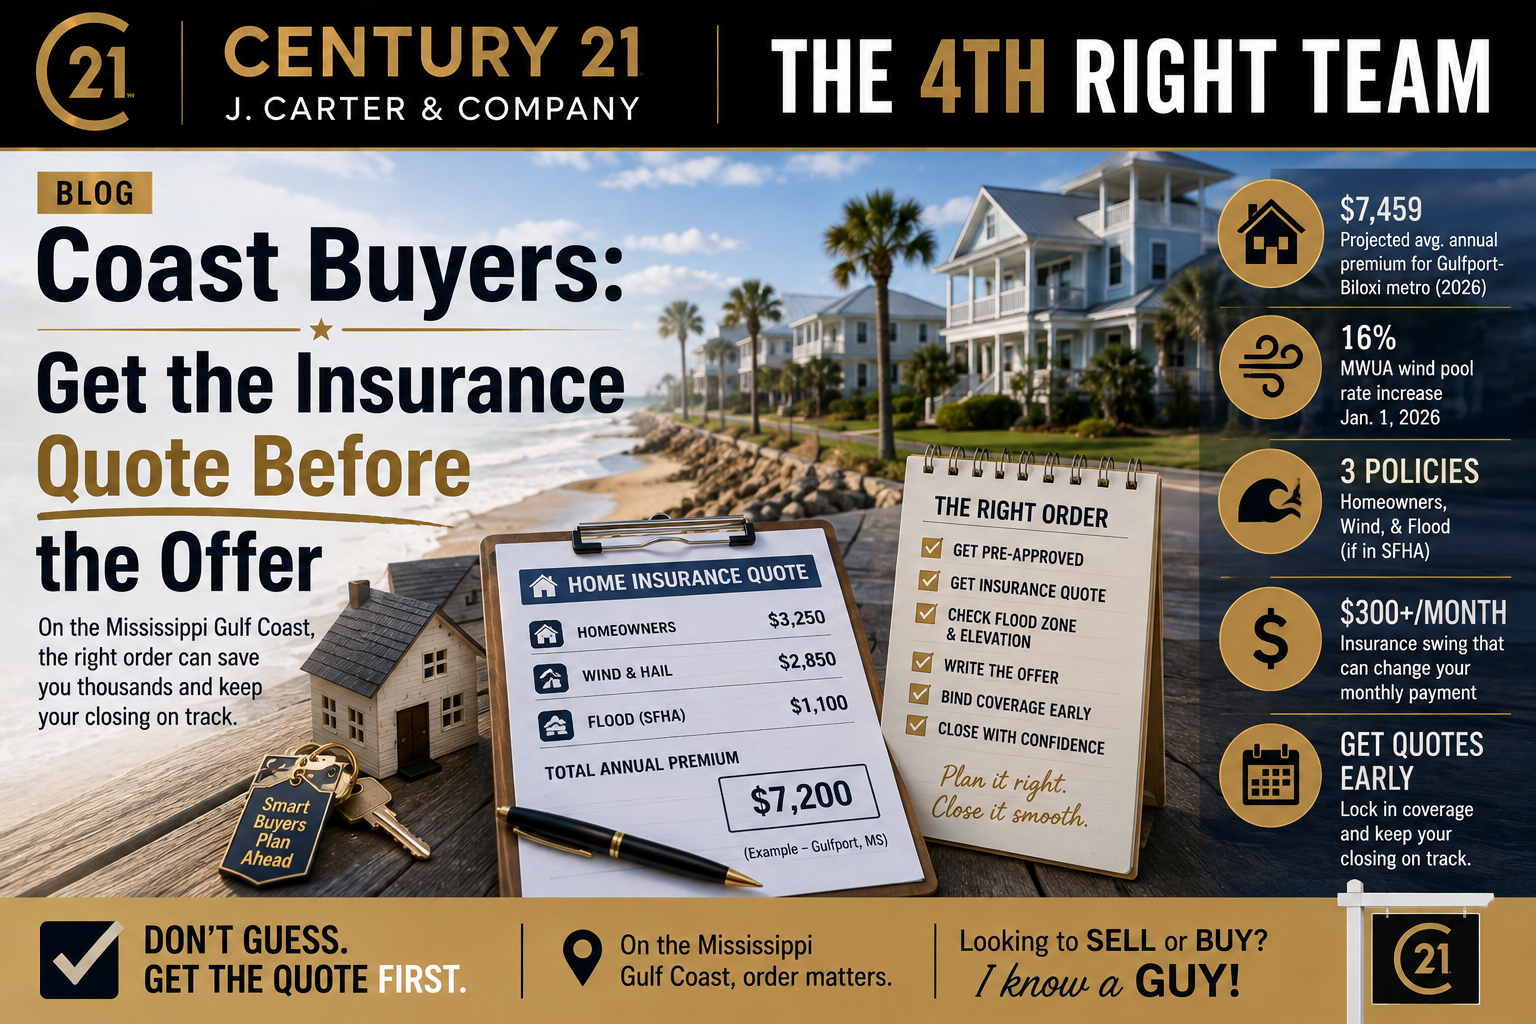
Quick Answer: On the Mississippi Gulf Coast, you get the insurance quote before you write the offer, not after. Insurance here isn't a rounding error on your escrow. Published estimates for Gulfport put annual homeowners premiums anywhere from about $3,700 to nearly $8,000, depending on the source and what's included, and that's before flood. That swing can move your monthly payment by $300 or more on the same house. Inland buyers shop the house first and the insurance last. That order gets people hurt here.
Here's what nobody tells you when you move down from Jackson or in from Texas. The house you can afford on this Coast isn't set by the sale price. It's set by the sale price plus insurance, flood, and taxes. Two houses on the same street can carry very different numbers depending on elevation, roof age, and distance from the water.
Why do Coast buyers get surprised by insurance?
Because the national playbook says get pre-approved, find a house, make an offer, then handle insurance during the inspection period. That works fine in Tupelo. It falls apart here.
Insurify's 2026 report put the average annual home insurance premium for the Gulfport-Biloxi metro at $7,284 in 2025, projected to reach $7,459 by the end of 2026. The statewide Mississippi average was projected around $3,833. So the Coast runs roughly double the rest of the state, and Mississippi is already a top-ten state for home insurance cost nationally. For more on what drives those numbers, see how much home insurance costs on the Coast.
Then there's wind. Most homeowners carriers on the Coast now include wind and hail in the policy. Some homes still need separate wind coverage, and a few end up in the Mississippi Wind Pool, whose rates went up 16% effective January 1, 2026. Flood is its own policy on top of that if the property sits in a Special Flood Hazard Area. None of these numbers show up on the listing.
What's the right order of operations?
This is the sequence that keeps deals together.
Talk to your lender first and get a real pre-approval. Then, before you fall in love with anything, get an insurance quote on the specific address you're considering. Check the flood zone and ask whether there's an elevation certificate. Then write the offer with the actual monthly number in front of you. Bind coverage during your inspection period, not the week of closing. And recheck the escrow figure before you sign the closing disclosure.
Six steps. The only one that's different from the rest of the country is putting the insurance quote before the offer instead of after. That one change is the whole post.
What should you ask your lender on the first call?
Ask for the pre-approval and the escrow estimate in the same conversation, and tell them the property is on the Coast.
Here's why that matters. A pre-approval letter tells you what a lender will loan you. It does not tell you what you can comfortably pay, because most automated escrow estimates default to a national or statewide insurance figure. Drop a Coast property into that model, and the estimate can be off by hundreds a month.
A good local lender knows this and will build the file with realistic Coast numbers. When you call, ask three things directly. What insurance figure are you using in my escrow estimate? Does that number include wind coverage? And does it include flood if this address needs it?
Then take that answer to an insurance agent and get a real quote on a real address. When your lender and your insurance agent are working the same numbers in week one, nothing surprises you in week six.
How do you get a real insurance quote before you make an offer?
You don't need to be under contract. You need an address.
Call a local independent agent, not a national quote tool. Give them the address, square footage, year built, and roof age. Ask whether wind is included in the homeowners quote, and ask for flood as a separate number so you can see what's driving the cost. Ask whether the carrier will write it at all, because on an older roof the answer is sometimes no.
Do this on your top two or three houses. One phone call each. It will occasionally save you from an offer you'd have regretted, which is worth more than the twenty minutes.
What does the flood zone have to do with your offer?
Plenty. Flood insurance in a Special Flood Hazard Area is a lender requirement, not an option, and the premium can swing a lot from one address to the next.
Ask whether the seller has an elevation certificate. If there is one, it can lower the flood premium a lot, and it's free to you. If there isn't, a new one costs money and takes time. That's a negotiating point worth knowing before you write the offer instead of after. And don't assume based on the neighborhood. FEMA expanded Gulfport's floodplain after Katrina, so a property that was low risk twenty years ago may not be now.
What happens if you skip this and find out later?
One of three things, and none of them are good.
You find out during the inspection period. Then you either eat a payment $250 higher than you planned, or back out and lose your inspection and appraisal money. Or you find out after your financing contingency expires, and walking away now costs you earnest money. Or you find out at the closing table when the escrow figure doesn't match your budget, and you sign anyway because everything's already packed.
That last one is the most common and the worst. Nobody backs out on closing day. They just live with a payment that's tighter than it should be. During hurricane season, the timing gets even tighter, so use our hurricane season closing checklist.
By the Numbers
$7,459: projected average annual home insurance premium for the Gulfport-Biloxi metro by end of 2026 (Insurify)
$7,284: Gulfport-Biloxi metro average in 2025 (Insurify)
$3,833: projected 2026 Mississippi statewide average (Insurify)
16%: MWUA wind pool rate increase effective January 1, 2026
6.66%: average 30-year fixed mortgage rate as of August 27, 2026 (Freddie Mac)
$206,371: average Gulfport home value (Zillow)
Roughly $47,000: the loan amount a $300 monthly payment covers at current rates
The Bottom Line
Get the insurance quote before you write the offer. That's the whole Coast workflow in one sentence. Your lender tells you what you can borrow, but your insurance agent tells you what you can actually afford. On this Coast, those two numbers are further apart than anywhere else in Mississippi. Make the calls in the same week, and you'll shop with real numbers instead of hopeful ones. If you're just getting started, our buyer's guide puts the rest of the Coast-specific steps in order.
Frequently Asked Questions
Can I get a homeowners insurance quote before I'm under contract?
Yes. You only need the property address and basic details like square footage, year built and roof age. Any local independent agent can quote it. You don't have to own it or be under contract.
Why is home insurance so expensive on the Mississippi Gulf Coast?
Hurricane and wind exposure. The coastal counties carry the highest premiums in the state. Most carriers now include wind and hail in the homeowners policy, but that wind risk is a big part of the price. Homes that can't get wind coverage from a private carrier may end up in the state Wind Pool.
Does my pre-approval account for Coast insurance costs?
Often not accurately. Many automated escrow estimates use a statewide or national average. Ask your lender specifically what insurance figure they used and whether it includes wind and flood.
Do I need flood insurance in Gulfport or Biloxi?
If the property is in a Special Flood Hazard Area and you're financing, your lender will require it. Even outside those zones, plenty of Coast homeowners carry it voluntarily because the premium is lower there.
What is an elevation certificate and why does it matter?
It documents your home's elevation relative to the base flood elevation. It can substantially lower your flood premium. Ask whether the seller already has one before you write your offer.
How much home does a $300 monthly difference actually cost me?
At current rates, roughly $47,000 in buying power. That's the gap between two houses on the same street with different roofs, elevations, or carriers.
Sources
Insurify 2026 Home Insurance Report, via the Sun Herald: Gulfport-Biloxi metro and Mississippi statewide average premiums
Mississippi Windstorm Underwriting Association, wind and hail coverage in the six coastal counties: https://msplans.com/node/6
Freddie Mac Primary Mortgage Market Survey: 30-year fixed rate as of August 27, 2026
Zillow: Gulfport average home value
FEMA Flood Map Service Center, Special Flood Hazard Areas and flood zone lookup: https://msc.fema.gov/portal/home
Kelsey Carlson, CISR Elite, Personal Lines Risk Advisor, Lemon Mohler Insurance: current carrier wind appetite, September 2026
Keep reading: Named Storm in the Gulf? What It Does to Your Closing and How Much Is Home Insurance on the Mississippi Gulf Coast?
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!