Blog > Worried About a Housing Crash on the Mississippi Gulf Coast?
By Randy Richardson, Broker Associate, The 4th Right Team at Century 21 J. Carter & Company.
Quick Answer: No, the Mississippi Gulf Coast isn't headed for a crash. A crash means a sharp, sudden drop in home values driven by forced selling, and none of the conditions that caused the 2008 collapse are in place here. Lending standards are far tighter than they were then, most Coast homeowners are sitting on real equity, and the job base behind the local market hasn't moved. What is happening is a slowdown. Homes take longer to sell, sellers negotiate more, and price growth has flattened. That's cooling, not cracking, and the two get confused constantly.
What Would an Actual Housing Crash Require?
Three things, usually. A wave of homeowners who can't make their payments, a flood of homes hitting the market at once because of it, and buyers who won't step in at any price. That's the 2008 sequence, and it started with loans that never should have been written.
That's the part that's different now. Lending standards tightened hard after 2008 and never loosened back up. The loans written over the last fifteen years went to people who documented income and could carry the payment. Without bad loans going bad in volume, you don't get the forced selling that starts a crash.
Are Home Prices Dropping on the Mississippi Gulf Coast?
Not in any meaningful way. Price growth has slowed across most of the Coast, and some cities are flat or slightly down while others are still creeping up. That's a normal market breathing after a few unusually hot years.
Prices also shift block to block here. A Gulfport number won't tell you what's happening in Ocean Springs or Bay St. Louis, and a citywide median won't tell you much about your street. If you're worried about your own home's value, the useful number is the one for your neighborhood, not a headline.
What's Actually Holding the Gulf Coast Market Up?
Jobs that don't leave. Keesler Air Force Base in Biloxi and NCBC Gulfport bring a steady rotation of people who need housing on orders, not on a whim. Ingalls Shipbuilding in Pascagoula anchors the eastern end of the Coast. The port, the casinos, and the tourism economy fill in around them.
That mix matters more than people realize. A market driven by speculation can crater when sentiment turns. A market driven by PCS orders, shipyard shifts, and hospital schedules has a floor under it, because those people are moving here whether or not the headlines are cheerful.
So What Is Changing Then?
Leverage. Buyers have more of it than they've had since 2020. Homes sit longer, price reductions are common again, and sellers are agreeing to concessions they would have refused two years ago.
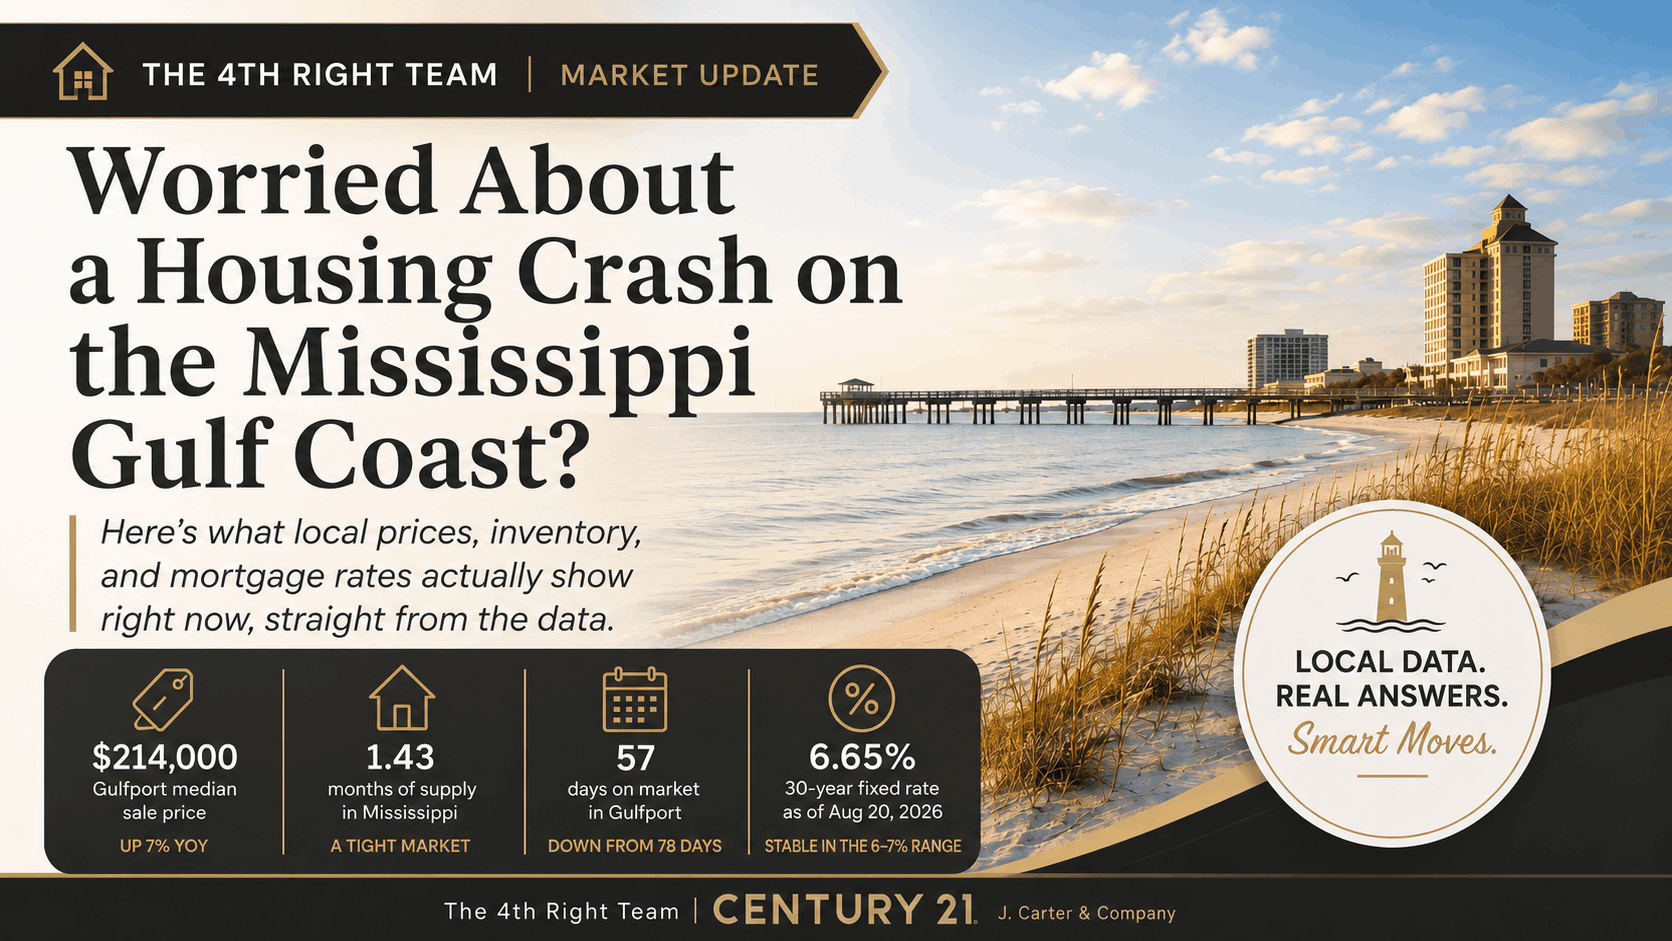
Rates are part of the story too. Freddie Mac's 30-year fixed averaged 6.76% on September 10, 2026, up from 6.71% the week before, and the Associated Press called that the highest reading in over 14 months. Higher rates cool demand. They don't crash prices on their own. Here's what waiting on rates actually costs you.
Is There a Real Risk on the Coast Worth Worrying About?
Yes, and it isn't a price crash. It's insurance. Wind Pool rates rose 16% effective January 1, 2026, and plenty of Coast homeowners now carry three separate policies between homeowners, wind, and flood.
That's the number that can price someone out of a house, and it's the number that can make a home hard to sell. A buyer who qualifies on the mortgage can fail on the insurance. If you want something to actually plan around, plan around that. Here's what Coast insurance runs, and here's why roof age is now part of the conversation.
What Does This Mean for Your Next Move?
It means you can plan instead of panic. Nobody needs to rush into a house out of fear that the market's about to fall apart, and nobody needs to sit out a move out of fear either.
If you're buying, you have room to negotiate and time to think. If you're selling, your home is still worth real money, but it needs honest pricing and clean insurance paperwork to move. Those are the two reasons Coast homes sit, and neither one is a crash.
By the Numbers
6.76% average 30-year fixed mortgage rate as of September 10, 2026 (Freddie Mac)
6.35% was the 30-year average one year earlier (Freddie Mac)
Highest 30-year reading in over 14 months (Associated Press, September 10, 2026)
16% MWUA wind and hail rate increase effective January 1, 2026 (Mississippi Insurance Commissioner Mike Chaney)
6 coastal counties are served by the Wind Pool: Hancock, Harrison, Jackson, Pearl River, Stone, and George (Mississippi Insurance Department)
For the full picture on where the Mississippi Gulf Coast market stands right now, see whether this is a buyer's or seller's market in 2026.
The Bottom Line
The Gulf Coast housing market isn't cracking. It's slowing, which is a different thing and a much less scary one. The conditions that caused 2008 aren't here, and the jobs that hold this market up aren't going anywhere. If you've been sitting on the sidelines waiting for the bottom to fall out, the numbers say that's not what's happening. Sellers can start with a free home value evaluation. Buyers can call us and we'll run real numbers on a real house, insurance included.
Frequently Asked Questions
Is the Mississippi Gulf Coast housing market going to crash in 2026?
Nothing in the current picture points that direction. A crash needs forced selling at scale, and tight lending standards since 2008 plus high homeowner equity make that unlikely here.
What's the difference between a cooling market and a crash?
A cooling market means homes take longer to sell and sellers negotiate more. A crash means values fall sharply because owners are forced to sell at once. The Coast is doing the first thing, not the second.
Why does the Gulf Coast behave differently than national headlines suggest?
Local markets don't move in lockstep with national averages. Steady demand from Keesler, NCBC Gulfport, Ingalls Shipbuilding, the port, and tourism keeps Coast prices behaving differently than the national number.
Will mortgage rates drop back to 3% or 4%?
No forecast worth trusting shows that in 2026. The 30-year has held mostly between 6% and 7% since late 2022 and sat at 6.76% on September 10, 2026.
What should Coast homeowners actually worry about?
Insurance, not a price crash. Wind Pool rates rose 16% in January 2026, and rising premiums do more damage to Coast affordability than any price movement has.
Sources
Freddie Mac Primary Mortgage Market Survey — 30-year fixed rate average, September 10, 2026, and year-earlier comparison
Associated Press — 30-year rate at highest level in over 14 months, September 10, 2026
Insurance Business — 16% MWUA rate increase effective January 1, 2026, announced by Insurance Commissioner Mike Chaney
Mississippi Insurance Department — Coastal county list
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!