Blog > What Actually Makes a Gulf Coast Home Harder to Sell in 2026?
By Randy Richardson, Broker Associate, The 4th Right Team at Century 21 J. Carter & Company.
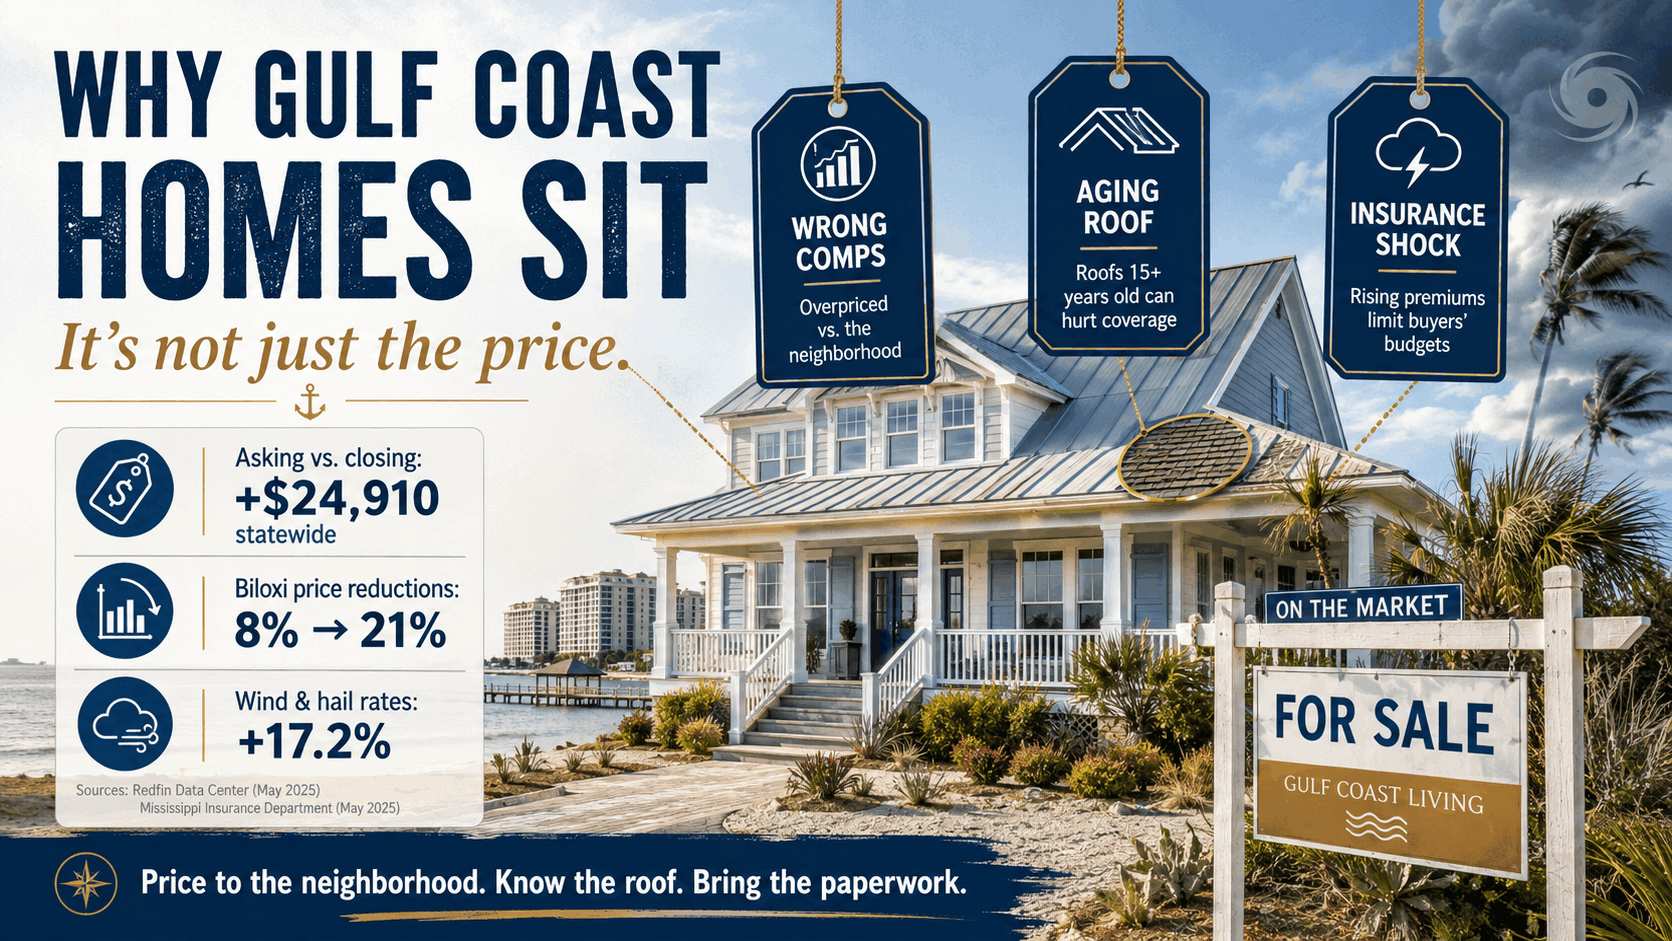
Quick Answer: Most Gulf Coast homes that sit on the market aren't badly overpriced. They're priced to the wrong comparison, usually the state median instead of their own neighborhood's numbers. Statewide, listings are asking about $24,910 more than homes are actually closing for. On the coast, roof age and insurance costs are doing even more damage, with Biloxi price reductions jumping from 8% of listings to nearly 21% in a year.
Is Your Home Priced to the Wrong Market?
Probably, if it's been sitting. Mississippi isn't one housing market. It's really three: the Gulf Coast, the Jackson metro, and the DeSoto County suburbs near Memphis. Each one moves differently, so pricing off a statewide number almost always backfires. Statewide, homes are asking about $24,910 more than what's actually closing, and that gap is coming from listings priced above their local band. In Gulfport, 61.9% of homes sold under asking price recently, with only 16.6% going over. If your agent priced your home using state or national data instead of what's closing three streets over, that's often step one of why it's still sitting.
Is Your Roof Making Insurance a Dealbreaker?
It might be, even if the roof looks fine from the ground. Roof age and condition are two of the biggest factors in coastal insurance underwriting. Carriers price and inspect around them, and an older roof can mean a higher quote, a required inspection, or a carrier that won't offer full replacement cost coverage. If a buyer's lender can't get an affordable quote, the deal can quietly die in underwriting instead of at the negotiating table. If your roof is older, the state's Strengthen Mississippi Homes program can put up to $10,000 toward a FORTIFIED roof, and here's who qualifies and how the lottery works.
Are Insurance Costs Scaring Off Buyers You Never Even Met?
Yes, more often than sellers realize. Insurance is the single most common way a Gulf Coast deal that looks fine on paper quietly stops working. Two homes with the same sale price can carry very different annual insurance costs depending on elevation, distance from the water, and roof condition, and none of that shows up in the listing price. For buyers using FHA financing, insurance premiums get folded into the monthly payment, so a high quote can shrink how much home a buyer actually qualifies for. Coastal wind and hail rates through the Mississippi Windstorm Underwriting Association rose an average of 17.2% this year. If you can hand a buyer's agent a real insurance quote up front instead of letting them guess, you remove a lot of the fear that makes buyers walk.
Are You Missing the Flood and Elevation Paperwork Buyers Now Expect?
If you don't have it ready, you're behind. An elevation certificate documents how high your home sits relative to base flood elevation, and it can make a real difference in what a buyer's flood insurance actually costs. Not every home needs one, but on the coast, buyers and their lenders are asking for it more often than they used to. Sellers who show up with a flood determination and an elevation certificate already in hand tend to move faster through underwriting, because the buyer isn't stuck waiting on paperwork mid-contract. If you don't know your home's flood zone status off the top of your head, that's worth confirming before you list, not after an offer comes in.
Is Deferred Maintenance Costing You More Than It Would to Fix?
Usually, yes. Buyers on the coast are more cautious than they were a couple years ago, and a home that needs obvious work gives them a reason to negotiate hard or walk. With Biloxi's price-reduction rate jumping from 8.01% to nearly 21% of listings in a year, sellers are already getting forced into cuts after the fact. It's almost always cheaper to fix a soft spot before listing than to drop your price $10,000 after an inspection flags it. Focus on the things that show up in an inspection report first: roof, HVAC age, water intrusion signs, and anything electrical. Cosmetic updates matter less than a clean inspection on the coast right now.
By the Numbers
Statewide asking prices average $24,910 above actual closing prices
Gulfport home sales: 61.9% closed under asking, only 16.6% closed over asking
Biloxi listings with price reductions: rose from 8.01% to 20.99% in one year
MWUA coastal wind and hail rate increase: 17.2% average this year
Strengthen Mississippi Homes roof grants: up to $10,000, launched July 1, 2026
FORTIFIED roof premium savings (comparable Louisiana program): average 22% a year
The Bottom Line
Homes on the Gulf Coast aren't sitting because buyers vanished. They're sitting because of pricing that doesn't match the neighborhood, roofs that scare off insurance underwriters, and paperwork buyers now expect to see up front. Fix those three things before you list, and your home competes with the ones that are actually selling, not the ones still waiting. If you're getting ready, see how we work with sellers.
Frequently Asked Questions
Why is my Gulf Coast home not selling even though it's priced close to similar homes?
It may be priced close to a statewide or regional average instead of your specific neighborhood's recent closings, which can still be thousands off from what's actually selling nearby.
Does my roof age really affect whether my home sells?
Yes. Many insurers limit coverage or require inspections on roofs over 15 years old, which can slow down or derail a buyer's financing even if the rest of the home shows well.
What is the Strengthen Mississippi Homes Program?
It's a state grant program that launched July 1, 2026, offering up to $10,000 for FORTIFIED roof upgrades, starting with homeowners insured through the Mississippi Windstorm Underwriting Association.
Do I need an elevation certificate to sell my home?
Not always, but it can speed up a buyer's flood insurance quote and underwriting, especially for homes near flood zones, so having one ready is a smart move before listing.
Is it worth fixing deferred maintenance before listing instead of pricing it in?
Usually yes, since inspection-driven price cuts tend to run higher than the cost of fixing the issue up front, and a clean inspection keeps more buyers from walking.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!