Blog > Selling a Mississippi Gulf Coast Home With an Assumable VA Loan
By Randy Richardson, Broker Associate, The 4th Right Team
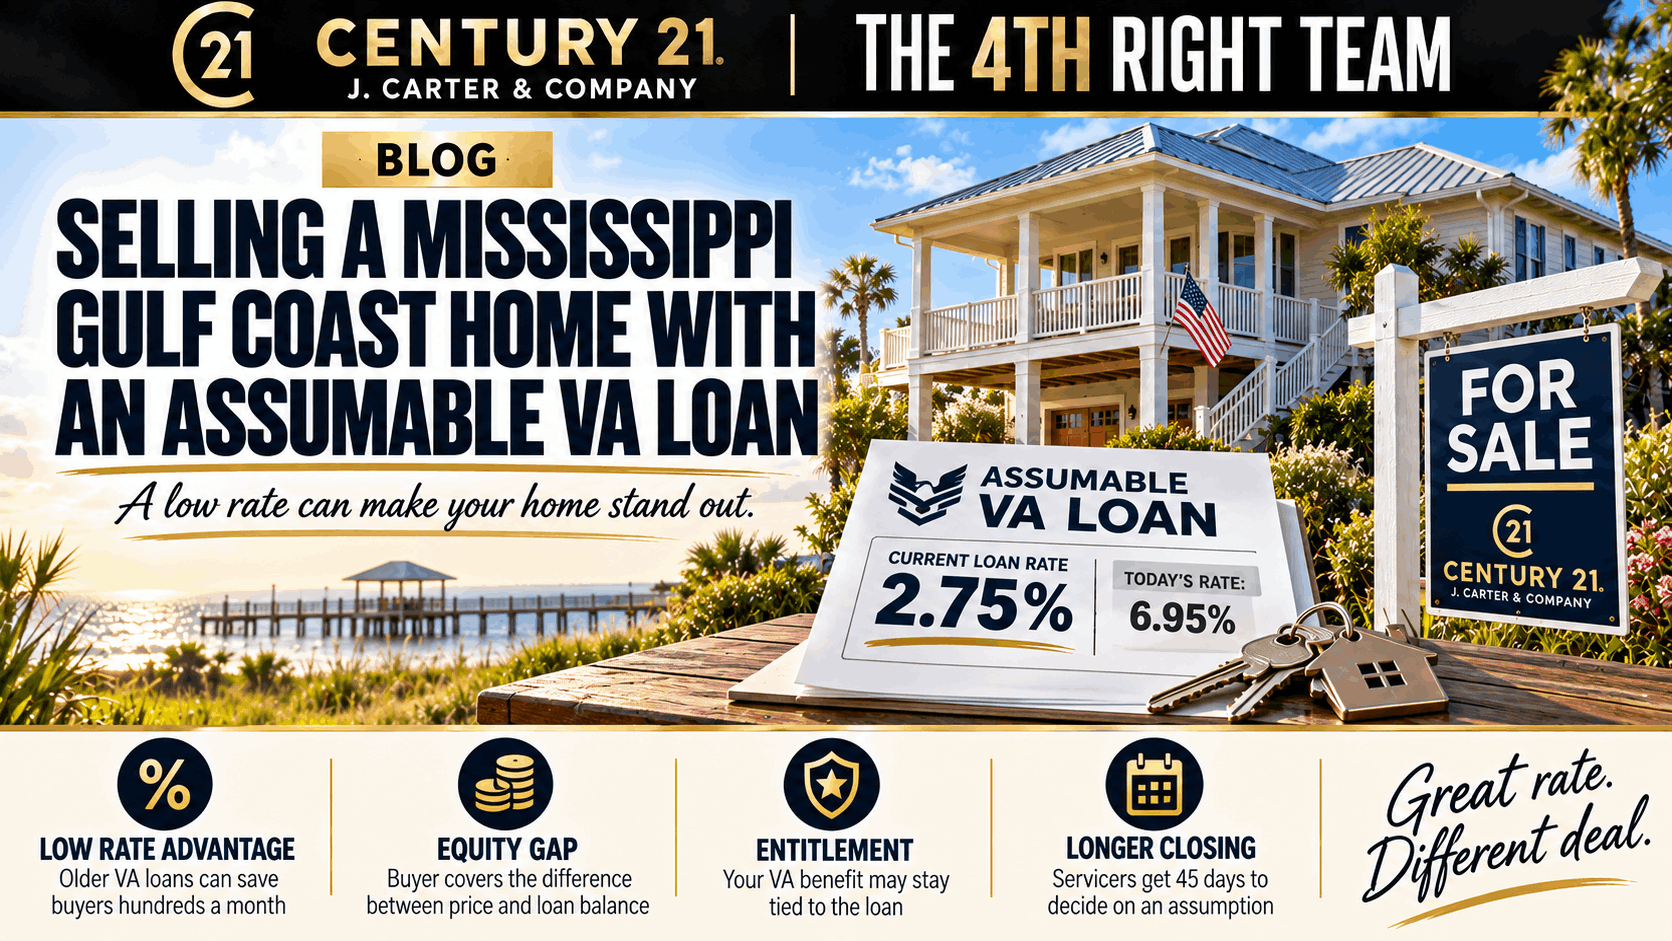
Quick Answer: If you're selling a Gulf Coast home with a VA loan, a buyer can take over your loan at your original interest rate, and they don't have to be a veteran to do it. With Freddie Mac's 30-year average at 6.95% as of September 17, 2026, a 2020 or 2021 VA rate can save a buyer hundreds of dollars a month, which makes your home stand out. The catch is that the buyer has to pay the difference between your price and your loan balance, usually in cash or with a second loan. Your VA entitlement also stays tied to the loan unless the buyer is an eligible veteran who substitutes theirs. Plan for a longer closing, since VA gives servicers 45 days just to decide on an assumption.
Can someone assume my VA loan when I sell my house?
Yes. VA loans are assumable, which means a buyer can take over your existing loan with the same rate, balance and remaining term. The buyer doesn't have to be a veteran. They do have to qualify with your loan servicer on credit and income, the same way they would for a new loan.
For a buyer, the draw is the rate. Many Coast homeowners who bought or refinanced in 2020 and 2021 have VA rates under 3%. Next to a new loan at today's rates, that's a real difference in the monthly payment. It also costs the buyer less up front in one way. The VA funding fee on an assumption is 0.5% of the loan balance, well below the fee on a new VA purchase loan.
How much is an assumable VA loan worth to a buyer?
Here's an example with round numbers. Say you bought in 2021 with a $250,000 VA loan at 2.75%. Your principal and interest is about $1,021 a month, and after five years you owe about $221,240. You sell for $300,000.
A buyer who finances the full $300,000 with a new VA loan at 6.95% would pay about $1,986 a month in principal and interest. A buyer who assumes your loan pays your $1,021, about $965 a month less. Run your own version on the mortgage calculator to see the gap on your numbers.
That's a strong selling point, especially for buyers who are tired of waiting for rates to come down. But look at the other side of the example. The buyer still owes you the $78,760 between your balance and the price.
What is the equity gap, and how do buyers cover it?
The equity gap is the difference between your sale price and what you owe. It's your equity, and an assumption doesn't pay it. The buyer has to bring it.
Some buyers bring cash. Others take out a second loan for the gap, and VA has issued guidance on how servicers handle assumptions with secondary financing. In the example above, if a buyer covered the $78,760 with a second loan at, say, 8.5% over 30 years, that loan would run about $606 a month. Added to your $1,021, they'd pay about $1,627, still roughly $359 a month less than a new loan at 6.95%.
The bigger your equity, the smaller your pool of buyers who can make it work. That's why an assumable loan helps most when the gap is manageable. It doesn't replace pricing the home right. Overpriced listings sit, even with a great rate attached.
What happens to my VA entitlement if a buyer assumes my loan?
This is the part military sellers need to understand before they agree to an assumption. Your VA entitlement stays tied to that loan until it's paid off, unless the buyer is an eligible veteran who substitutes their own entitlement for yours. If they do, VA can restore your entitlement.
If a non-veteran assumes your loan, your entitlement stays committed. That can limit how much you can borrow with a VA loan on your next home without a down payment. If you're selling on PCS orders and plan to use your VA benefit at the next base, talk to your lender about your remaining entitlement before you accept an offer.
Also make sure you get a release of liability. When the servicer approves a qualified buyer, you should be released from personal liability on the loan. Ask for it in writing, so a future default by the buyer can't come back to you.
How long does a VA loan assumption take to close?
Longer than a regular sale. In a December 2023 circular, VA told servicers with automatic authority that they're expected to decide on a complete assumption package within 45 days, and it warned of consequences for servicers that don't. That's 45 days for a decision, before closing is scheduled.
Build that into the contract. Give the assumption approval its own timeline, and don't promise a 30-day close. If you're working against a report date, factor it in when you choose between offers, because a buyer with a new loan may close sooner even if their offer looks a little smaller.
How do I market a home with an assumable VA loan?
Say it clearly in the listing. Put the rate, the approximate balance and the fact that the loan is assumable right up front, because buyers won't find it otherwise. Many sellers don't even know their loan can be assumed, so buyers who are looking for one have to hunt.
Then do the math for them. Show the estimated monthly payment on the assumed loan next to a new loan at today's rate, and show the cash it takes to cover the equity gap. A buyer who can see the savings in dollars is much more likely to book a showing than one who has to figure it out.
Know your own numbers too. Get a payoff figure from your servicer and run a seller net sheet so you can compare an assumption offer against a conventional one on what you'd actually walk away with.
By the Numbers
VA funding fee on an assumption: 0.5% of the loan balance
VA's decision window for servicers with automatic authority: 45 days
Freddie Mac 30-year fixed average, as of September 17, 2026: 6.95%
Example P&I on an assumed $250,000 loan at 2.75%: about $1,021 a month
Example P&I on a new $300,000 loan at 6.95%: about $1,986 a month
Example equity gap on a $300,000 sale: about $78,760
The Bottom Line
An assumable VA loan can make your home the best deal on the block, but only for buyers who can cover your equity and wait out a longer closing. Market the rate clearly, protect your entitlement and liability, and weigh assumption offers against conventional ones on your net, not just the price.
If you're thinking about selling a home with a VA loan, start with a home value evaluation. Then I'll show you how I list and market an assumable loan so the right buyers find it.
Frequently Asked Questions
Does a buyer have to be a veteran to assume my VA loan?
No. Any buyer who qualifies with your loan servicer on credit and income can assume a VA loan. Only an eligible veteran can substitute their entitlement for yours.
Do I get my VA entitlement back if someone assumes my loan?
Only if the buyer is an eligible veteran who substitutes their entitlement. Otherwise your entitlement stays tied to the loan until it's paid off, which can limit your next VA purchase.
How long does a VA loan assumption take?
Longer than a regular closing. VA expects servicers with automatic authority to decide on a complete assumption package within 45 days, and closing comes after that.
Who pays the equity gap on a VA assumption?
The buyer. They pay the difference between the sale price and your loan balance, usually in cash or with a second loan.
Sources
Assumption procedures, entitlement substitution and restoration: VA Circular 26-23-10, Assumptions
45-day decision expectation and non-compliance: VA Circular 26-23-27, Non-Compliance in Processing Assumptions (December 2023)
Assumptions with secondary financing: Alston & Bird, summary of VA Circular 26-24-17 (August 2024)
0.5% assumption funding fee: VA, Funding Fee and Closing Costs
30-year fixed rate as of September 17, 2026: Freddie Mac Primary Mortgage Market Survey
Example payments, balance and equity gap: calculated for this post, illustrative only
About the Author
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He serves buyers and sellers across the Mississippi Gulf Coast.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!