
Blog > VA Appraisal Problems in Older Coast Homes: What Actually Gets Flagged
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Keesler AFB PCS guide.
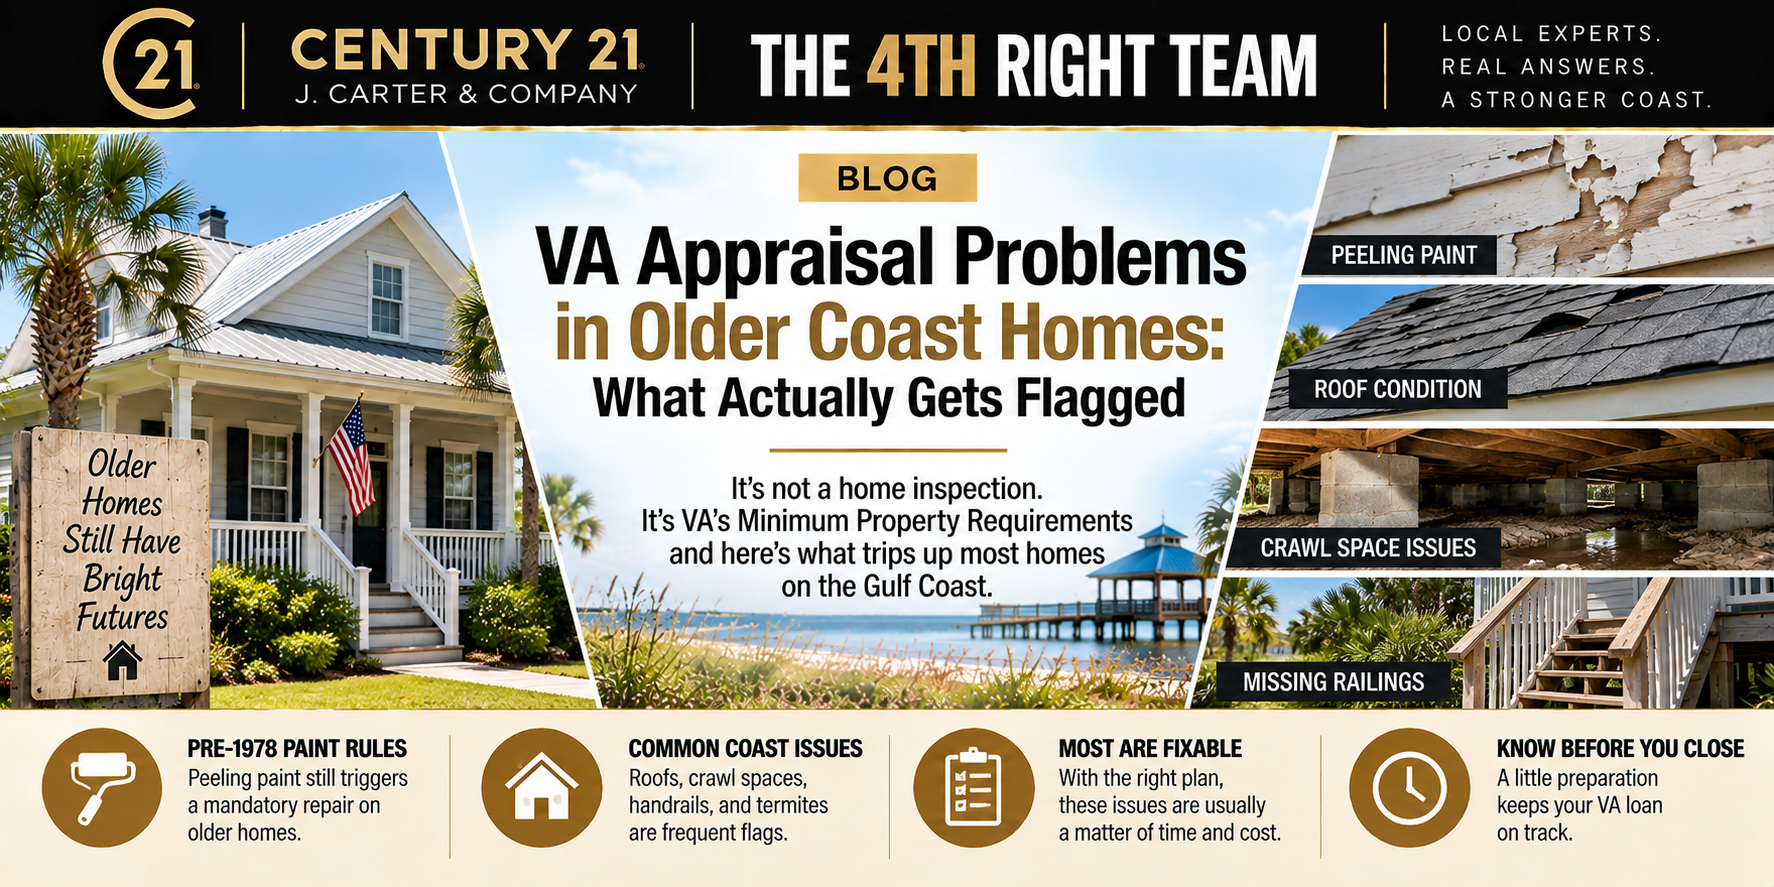
Quick Answer: A VA appraisal isn't a home inspection. It's a value opinion plus a check against VA's Minimum Property Requirements, and the MPRs are what stop closings on older Mississippi Gulf Coast homes. VA updated those rules with Change 46, effective for appraisals ordered on or after May 1, 2026, and the update helped newer homes considerably. It changed nothing for pre-1978 homes. Peeling paint on a house built before 1978 still triggers a mandatory repair, and the VA appraiser has to certify the fix. On this coast, the repeat offenders are paint, roof condition, wet or unvented crawl spaces, missing handrails on elevated stairs, and termite findings. Almost all of it is fixable. It just costs time, and time is what kills contracts.
What does a VA appraiser actually check?
Two jobs at once, and people mix them up constantly.
Job one is value: what the house is worth based on comparable sales. Job two is a condition check against VA's Minimum Property Requirements, which exist to confirm the home is safe, sound, and sanitary before VA will guarantee the loan.
The appraiser is not an inspector. They don't test the furnace, they don't pull the panel cover, and they don't crawl under the house. They look. They're required to look into the attic if there's a hatch, but they don't have to climb in or move insulation. They look into the crawl space without entering it.
That's why a home inspection before the appraisal is the single best move a VA buyer can make. It tells you what the appraiser is going to see, while you still have time to negotiate. Getting a VA purchase to the finish line is mostly about not being surprised.
Did the 2026 VA appraisal changes help older homes?
Not much. Change 46 to VA Pamphlet 26-7, Chapter 12 took effect for appraisals ordered on or after May 1, 2026. It's truly good news, but it's aimed at a different house than the one you're looking at.
Under the update, defective paint on homes built in 1978 or later is treated as cosmetic and no longer generates a mandatory repair condition. Detached structures like garages and sheds no longer have to meet MPRs at all, though an appraiser can still flag a real safety hazard under the general hazard provision. Non-vented fireplace requirements no longer apply.
Now the part that matters for older Coast homes. Pre-1978 lead paint requirements are fully intact. Any defective paint on a pre-1978 main dwelling still has to be cleaned, scraped, and repainted with two coats of non-leaded paint, and the VA-assigned appraiser has to certify completion.
One more detail worth knowing: the effective date is the order date, not the closing date. An appraisal ordered April 28 runs under the old rules even if it closes in June.
Why is paint the number one problem on the Coast?
If your house was built before 1978 and it has wood siding, salt air, and Gulf Coast humidity, paint fails. That's not a maintenance failure. That's physics.
VA assumes lead is present on any pre-1978 home. The appraiser doesn't test for it. They look for cracking, chipping, or peeling, and if they find it, it's a repair condition. Not a note. A condition that has to be corrected before the lender issues a clear to close, then re-certified by the appraiser.
The re-certification step is what gets people. You scrape and paint on a Tuesday, and then you wait for the appraiser to come back out and sign off. That round trip can add one to three weeks to a closing.
Sellers, this is the cheapest thing on this entire list to handle in advance. A few hundred dollars of scraping and paint on a pre-1978 house, done before you list, removes the most common VA repair condition there is. A VA buyer can pay full price with zero down, so turning them away costs you real money. Unresolved condition issues are one of the things that make a Coast home harder to sell.
What do VA appraisers flag on roofs, crawl spaces, and handrails?
These three come up on Coast homes constantly.
Roof. Roofing is the single most common source of MPR conditions nationally, and down here it's compounded by wind and salt. VA requires the roof to be in good shape with reasonable future utility. VA doesn't set a number, but lenders often want to see three to five years of remaining life. Active leaks, missing shingles, and water-stained ceilings all generate conditions. If a replacement is needed and there are three or more layers of shingles, every layer has to come off first. Since you're going to be dealing with the roof anyway, look at whether the Strengthen Mississippi Homes grant applies. And understand that roof age is separately an insurance problem on this coast.
Crawl space. VA requires the crawl space to have access, be clear of debris, be adequately vented, and be dry. On the Gulf Coast, dry is the hard one. Standing water, blocked or missing vents, and visible moisture damage all generate conditions. Excessive dampness, leaks, and rot are named in VA's own hazard examples, right alongside termites. If you're buying a raised or pier and beam home here, assume the appraiser is going to look under it.
Handrails. This one surprises people. Missing handrails on stairs with more than three risers is a routine flag, and elevated homes on this coast have stairs by definition. Whether the house was raised after Katrina or built high from the start, check the handrails before the appraiser does. It's a cheap fix that turns into a two-week delay if nobody catches it early.
How do termites, heat, and AC affect a VA appraisal?
Mississippi is a required wood-destroying insect inspection zone, so the WDI report is part of the file. Active infestation, fungal damage, or dry rot generate conditions, and treatment plus any repairs generally have to be completed and documented before the lender funds. Here's more on why Formosan termites are a Coast problem no matter what foundation you have.
Heat is required. The home needs a heating source that can maintain adequate temperature, including keeping plumbing areas at 50 degrees. If a wood stove is the primary heat source, there has to be a conventional system as well.
Air conditioning is where people get it backwards. VA has no minimum property requirement for air conditioning, regardless of climate. None. But if a system is installed and it doesn't work, that can generate a repair condition. So on a Coast house in August, a broken AC unit is a bigger problem than no AC unit, which is exactly as strange as it sounds.
Practical tip that saves files: make sure the utilities are on at the time of the appraisal. Appraisers are increasingly strict about systems being operational, and a furnace they can't test because the gas is off generates a condition that never needed to exist.
What if the VA appraisal comes in low?
Everything above is about condition. The other way a VA appraisal derails a Coast deal is value, and it's a different animal.
Our comps are messy. On a lot of Coast streets, you've got original homes sitting next to post-Katrina rebuilds, and those are not the same house even when the square footage matches. An appraiser pulling comps without accounting for that can land low.
If the value comes in under contract price, that's a separate conversation from repairs, and there are established processes for challenging it. Talk to your lender about a reconsideration of value rather than assuming the number is final. And know your options going in: renegotiate, bring the difference in cash, or walk under the VA amendatory clause.
How do you get ahead of VA appraisal problems?
Order a home inspection before the appraisal, always. Walk the exterior of any pre-1978 house looking for paint failure. Check handrails on every set of stairs with more than three steps. Look under the house. Confirm utilities will be on.
If conditions come back, get quotes before you negotiate. Most MPR items are small money, and the fight is usually about who pays and how fast, which is what credits and concessions exist to solve. And build the re-inspection into your timeline, because a corrected condition still needs the appraiser to come back and certify it.
None of this is a reason to avoid an older Coast home or a VA buyer. Most of these deals close. The ones that don't usually had somebody find out in week four what they could have found out in week one.
By the Numbers
May 1, 2026: effective order date for Change 46 to VA Pamphlet 26-7, Chapter 12
1978: the lead paint dividing line; defective paint on older main dwellings still requires mandatory repair
2 coats: non-leaded paint required over remediated surfaces, certified by the VA appraiser
3 risers: the stair threshold above which missing handrails commonly generate a repair condition
3 to 5 years: remaining roof life many lenders want to see, though VA sets no fixed number
3 layers: shingle layers at or above which all must be removed before a new roof goes on
50°F: minimum temperature the heating system must maintain in plumbing areas
0: VA minimum property requirements for air conditioning, in any climate
1 to 3 weeks: typical delay added by a roof certification or lead paint remediation
Order date, not closing date: determines which version of the rules applies
The Bottom Line
The VA appraisal on an older Coast home is not a mystery. The same handful of things get flagged over and over: paint on a pre-1978 house, roof condition, a damp crawl space, missing handrails, and termites.
Every one of those is knowable before the appraiser ever pulls up. Get the inspection first, walk the exterior yourself, and price the fixes before you're negotiating under a deadline.
Sellers, the flip side is worth saying plainly. A VA buyer can pay full price with nothing down. Spending a weekend on paint and handrails before you list is a smaller investment than losing that buyer.
If you're listing an older home and want to know where you stand, start with a home value estimate and look at the selling process. If you're buying with VA, our buyer's guide covers the timeline, you can see what's listed in Biloxi, and a local agent can walk a house with you and call the flags before you write.
Frequently Asked Questions
Is a VA appraisal the same as a home inspection?
No. A VA appraisal establishes value and checks the property against VA's Minimum Property Requirements. The appraiser does not test systems, enter the crawl space, or move insulation in the attic. A separate home inspection is strongly recommended and should be scheduled before the appraisal.
Did the 2026 VA appraisal changes help older homes?
Not really. Change 46, effective for appraisals ordered on or after May 1, 2026, made defective paint on homes built in 1978 or later cosmetic and removed MPR compliance for detached structures. Lead paint requirements on pre-1978 main dwellings remain fully in place and unchanged.
What is the most common VA appraisal repair condition?
Roofing issues are the most common single source nationally, and peeling or chipping paint on pre-1978 homes is close behind. On the Mississippi Gulf Coast, paint failure on older wood-sided homes is especially frequent because of salt air and humidity.
Does VA require air conditioning?
No. VA has no minimum property requirement for air conditioning in any climate. However, if a system is installed and non-functional, that can generate a repair condition. A broken unit is a bigger problem than no unit at all.
What does VA require of a crawl space?
Access, clearance of debris, adequate ventilation, and dryness. Standing water, blocked vents, and evidence of moisture damage generate conditions. VA's hazard examples specifically name excessive dampness, leaks, rot, and termites.
Who pays for VA appraisal repairs?
It's negotiable between buyer and seller and often handled through credits or concessions. The practical constraint is timing, since a corrected condition typically requires the VA-assigned appraiser to return and certify completion before the lender can issue a clear to close.
What happens if the VA appraisal comes in below the contract price?
That's a value issue rather than a condition issue. Options generally include requesting a reconsideration of value through the lender, renegotiating the price, bringing the difference in cash, or exercising the VA amendatory clause. Coast comps can be complicated by original homes sitting beside post-Katrina rebuilds.
Sources
VA Lender's Handbook, Pamphlet 26-7, Chapter 12, Minimum Property Requirements: https://www.benefits.va.gov/warms/pam26_7.asp
U.S. Department of Veterans Affairs, VA home loan program: https://www.va.gov/housing-assistance/home-loans/
Veterans United, Understanding VA Minimum Property Requirements, including the May 1, 2026 changes: https://www.veteransunited.com/valoans/understanding-the-vas-minimum-property-requirements/
Veterans United, VA appraisal deal breakers and lead-based paint requirements, May 2026: https://www.veteransunited.com/realestate/4-va-appraisal-dealbreakers-and-how-to-handle-them/
VA Loan Network, 2026 VA Minimum Property Requirements and Change 46, July 2026: https://valoannetwork.com/va-minimum-property-requirements/
USMilitary.org, VA Minimum Property Requirements and common repair triggers, June 2026: https://usmilitary.org/va-minimum-property-requirements/
EPA, lead-based paint and the 1978 threshold: https://www.epa.gov/lead
Keep reading: Using a VA Loan to Buy Near Keesler or NCBC Gulfport and Keesler AFB PCS Guide: Buying a Home Near Biloxi in 2026
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He works with buyers and sellers across the Mississippi Gulf Coast, from Bay St. Louis to Pascagoula and north of I-10.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!