Blog > Mississippi's $10,000 FORTIFIED Roof Grant: Who Qualifies?
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Mississippi Gulf Coast home insurance guide.
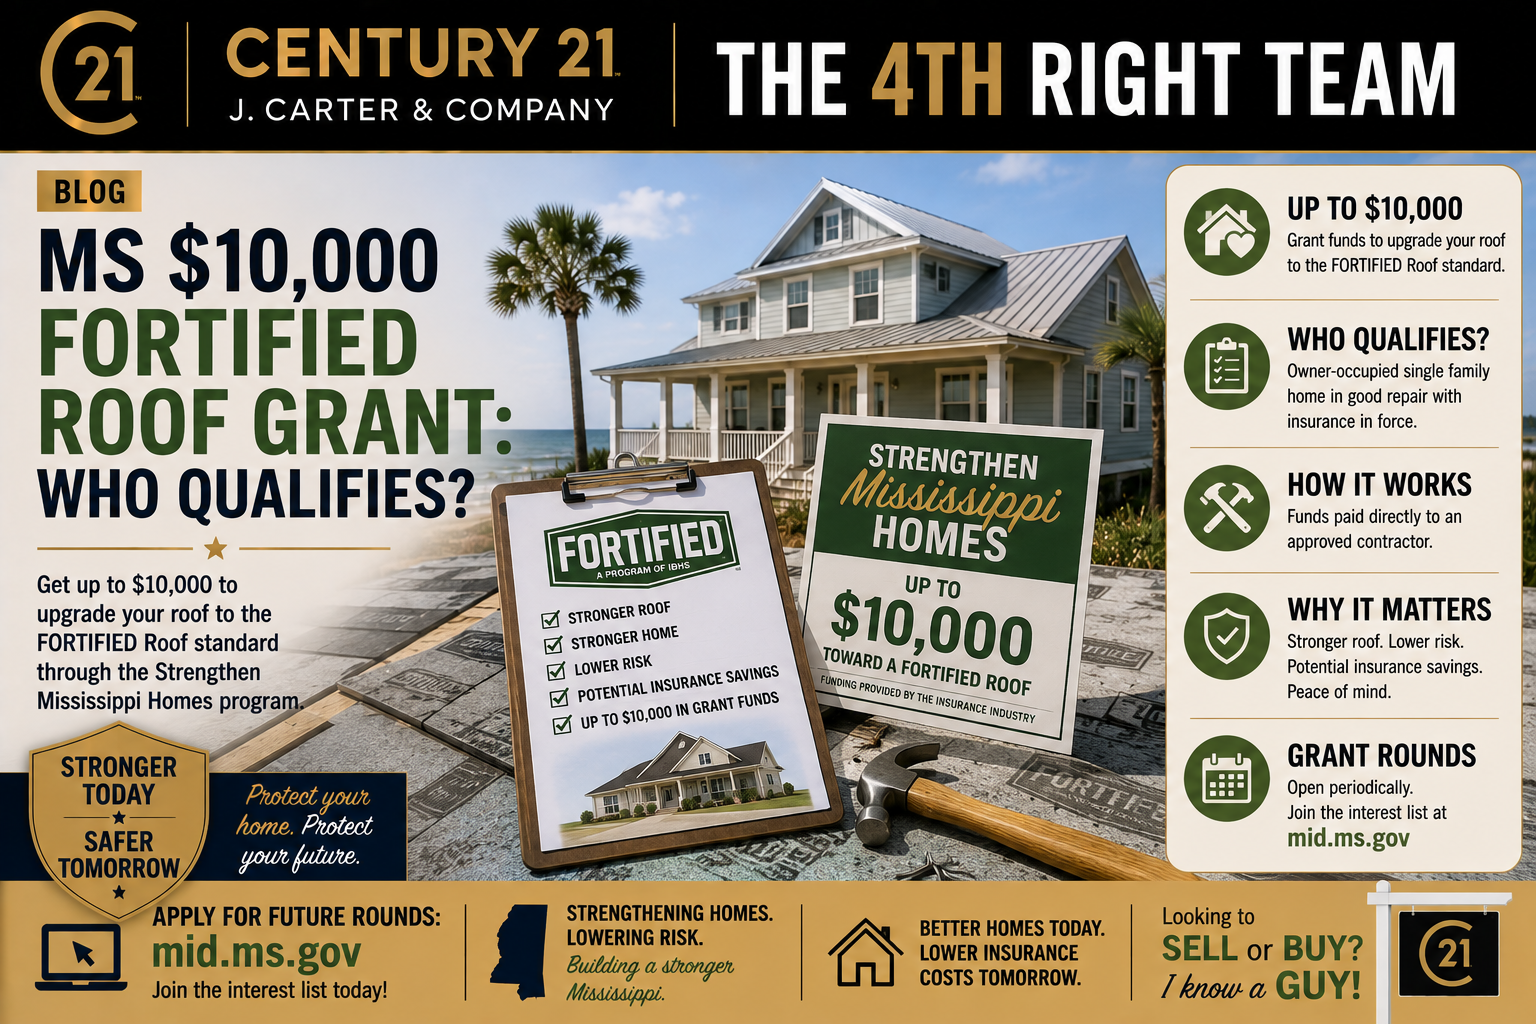
Quick Answer: The Strengthen Mississippi Homes program is live again. Senate Bill 2409 from the 2026 Regular Session funded it, effective July 1, 2026, and the Mississippi Insurance Department runs it. The grant covers up to $10,000 toward upgrading your roof to the IBHS FORTIFIED Roof standard, and it's paid straight to your contractor when the job's done. It's not a loan, and you don't pay it back. Right now, what's open is an interest form, not an application, and the first phase is aimed at Mississippi Windstorm Underwriting Association policyholders on the Coast. One grant per household.
Is the Strengthen Mississippi Homes grant still available in 2026?
Yes. Funding was suspended in 2025, which is why you may have read somewhere that the program was dead. The 2026 Legislature brought it back. The Mississippi Insurance Department says funding for the grant program was made available under Senate Bill 2409 from the 2026 Regular Session, and that the money comes from the insurance industry in Mississippi. It's not General Fund money, and it's not tied to a federal program.
One note if you followed the bill in the news. Some coverage of earlier versions mentioned a $15,000 cap. What MID actually publishes is up to $10,000. Go with MID's number, because that's what a homeowner will be told.
How much is the FORTIFIED roof grant worth?
Up to $10,000 toward the roof upgrade. MID pays the contractor directly once the project's finished and the paperwork is in, including the FORTIFIED certificate from IBHS. You never touch the money.
Two costs are on you. The evaluator's fee isn't included in grant funding, and you pay it out of pocket before the work starts. And if your bids come in higher than your grant award, you cover the difference. That's worth knowing before you fall in love with the idea. A Coast reroof can run well past $10,000, and this grant is help, not a free roof. If you're already weighing what your roof's age is doing to your insurance, that's the math to run first.
Who qualifies for the Strengthen Mississippi Homes grant?
You have to own and live in the home as your primary residence, and it has to be a single-family house. MID is direct about what doesn't count. Townhomes, rental property, condominiums, and mobile homes don't qualify for the grant program.
There's a second requirement that catches a lot of Coast homeowners off guard. If your home sits in one of the six coastal counties, Hancock, Harrison, Jackson, Pearl River, Stone, or George, it has to be in a jurisdiction that has adopted and actively enforces a building code that meets or exceeds the FORTIFIED roof standard. That's a real filter. If you're outside city limits in an area that hasn't adopted that code, you may not be eligible at all, no matter how good your house is.
The rest of the requirements are about insurance and condition. Your home has to be in good repair. You need proof of an in-force homeowners policy. You need flood insurance if you're in a special flood hazard area, which is a good reason to know what your elevation certificate says. You have to pay for a home evaluation from a certified FORTIFIED evaluator approved by the program. And you have to show an in-force wind policy on the home when the mitigation work is finished.
Can I apply right now?
Not exactly, and this is the part most articles get wrong. What's open right now is an interest form. MID states plainly that submitting it doesn't count as a grant round application and doesn't guarantee you'll be selected or funded. They use it to gauge demand and plan future rounds.
Actual grant rounds open periodically through the year, and MID announces the dates in advance. So the move is to get your interest form in, then watch their site.
Reporting from this summer indicates the first phase is limited to Mississippi Wind Pool policyholders in Hancock, Harrison, and Jackson counties who've held an MWUA policy for three straight policy years, with a broader statewide rollout expected in early 2027. That phase detail comes from FORTIFIED evaluator firms working the program, not from MID's published FAQ. Confirm it with MID before you count on it either way.
How does the process actually work?
Submit the interest form. If you're selected for a grant round, MID notifies you and gives you a list of approved evaluators to choose from. You hire and pay the evaluator. You pick a contractor from the program's approved list, and their system notifies that contractor they've got the job.
Don't get ahead of it. You can't do the work yourself, you can't hire a program contractor before the grant is awarded, and any work done outside the program's scope isn't covered. If you decide to walk away, you can opt out any time before you sign a contract. But you have to notify the program in writing within 30 days of your award letter, and your evaluator fee isn't refunded.
One more thing worth planning around. A FORTIFIED designation is good for five years. After that, it needs a re-designation inspection to confirm nothing substantial has changed and the roof covering is still within its life expectancy.
Why would a Coast homeowner bother?
Because the whole point of the program is lower insurance rates. MID says the program's mission is to protect property and lower insurance costs in Mississippi. On the Coast, insurance is often the line that breaks a budget. A stronger roof and a FORTIFIED certificate can change what you pay every year for a long time.
It matters at sale time too. A FORTIFIED roof is something a buyer's agent can put in front of a buyer who's nervous about wind coverage, and roof age is one of the real reasons Coast homes sit. If you're thinking about selling in the next few years, this is the kind of improvement that does double duty.
By the Numbers
$10,000: the maximum grant per recipient toward a FORTIFIED Roof upgrade (Mississippi Insurance Department)
1: grant per household (Mississippi Insurance Department)
6: coastal counties with the building code requirement: Hancock, Harrison, Jackson, Pearl River, Stone, and George (Mississippi Insurance Department)
July 1, 2026: the effective date of the funding under Senate Bill 2409, 2026 Regular Session (Mississippi Legislature)
5 years: how long a FORTIFIED designation lasts before re-designation (Mississippi Insurance Department)
30 days: your window to opt out in writing after a grant award letter (Mississippi Insurance Department)
The Bottom Line
The money's real and it's back, but it isn't first come, first served, and it isn't open to everybody. Get the interest form in, find out whether your jurisdiction's building code qualifies you, and budget for the evaluator fee and whatever your roof costs above $10,000. If you're weighing a roof against a move, or wondering what a FORTIFIED roof would do to your home's value, give us a call or start with a free home value evaluation.
We're REALTORS, not the Insurance Department. Program rules, eligibility, and grant round timing come from MID and can change. Confirm the current details with them before you spend a dollar.
Frequently Asked Questions
Do I have to pay the Strengthen Mississippi Homes grant back?
No. MID says grants are not loans and don't need to be repaid. The purpose is to lower insurance rates and make homes more resistant to storm damage. Only one grant per household.
Does my condo or mobile home qualify?
No. MID lists townhomes, rental property, condominiums, and mobile homes as ineligible. It has to be an owner-occupied single-family home you claim as your primary residence.
Who do I call with questions?
Don't call. MID directs questions to SMH@mid.ms.gov and says you don't need to phone them. Email is the channel that actually gets answered.
Does the grant cover the whole roof?
Only up to $10,000, and only the FORTIFIED Roof scope. Anything beyond that is on you, and any extra work you want done requires a separate contract with your contractor outside the grant.
Will a FORTIFIED roof actually lower my insurance?
That's the program's stated purpose, and Mississippi insurers are required to notify policyholders about discounts and credits tied to FORTIFIED construction. What you personally save depends on your carrier, your wind policy, and your home. Ask your agent for a quote both ways before you commit.
Sources
Mississippi Insurance Department, Strengthen Mississippi Homes (grant amount, eligibility, coastal county building code rule, interest form status, evaluator and contractor rules, opt-out window, FORTIFIED designation term): https://www.mid.ms.gov/mississippi-insurance-department/preparedness/mitigation/smh/
Mississippi Insurance Department, Strengthen Mississippi Homes FAQ: https://apps.mid.ms.gov/mitigation/strengthen-mississippi-homes.aspx
Mississippi Legislature, Senate Bill 2409, 2026 Regular Session (program authorization and funding)
Fortified Inspections, reported first-phase eligibility for MWUA policyholders, July 2026: https://fortifiedinspections.com/strengthen-mississippi-homes-grant-program/
Keep reading: Roof Age and Insurance: What Coast Sellers Must Know and What Is the Mississippi Wind Pool, and Do You Need It?
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!