Blog > The Pre-Listing Fixes That Make Your House Easier to Insure
By Randy Richardson, Broker Associate, The 4th Right Team
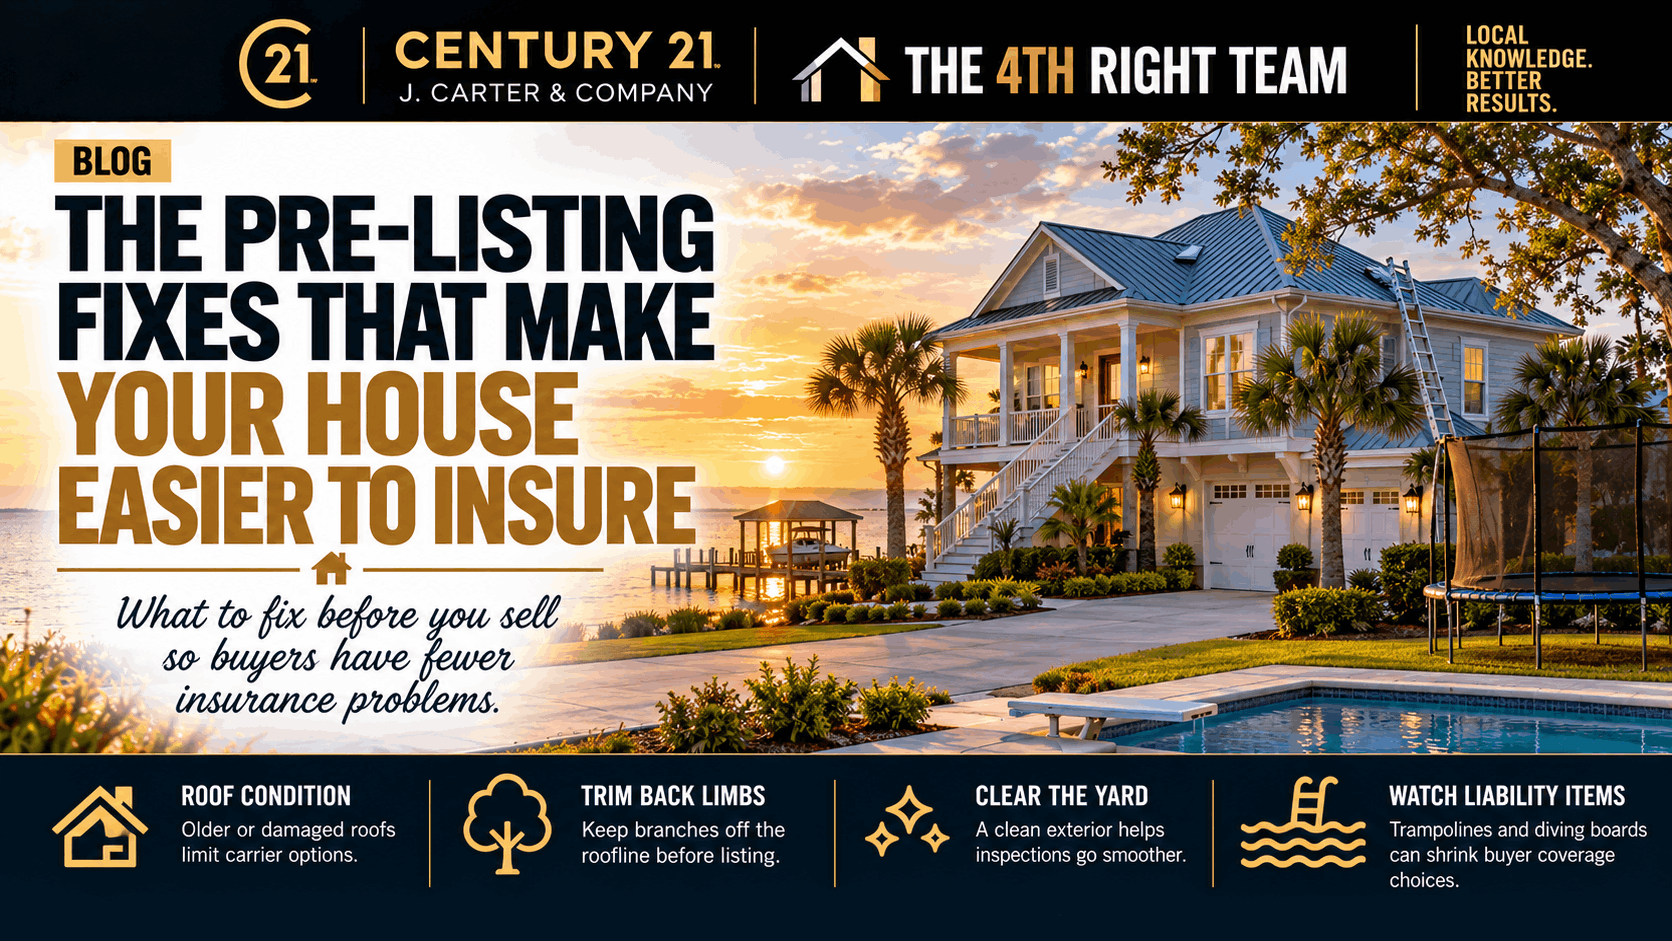
Quick Answer: On the Mississippi Gulf Coast, the best pre-listing repairs are the ones that make your house easier for a buyer to insure. A local insurance advisor ranks the top three this way: replace an older roof, trim tree limbs away from the roofline and the house, and clear debris out of the yard. Then look at the liability features that narrow a buyer's carrier options, like a pool with a diving board or slide, or a trampoline. Your buyer's lender won't close without an insurance binder, so anything that makes a carrier hesitate can slow or stop your sale.
Most "fix this before you sell" lists are about paint, fixtures and curb appeal. Those still matter. But on the Coast, there's a second audience looking at your house, and it's not the buyer. It's the buyer's insurance company.
Why does insurance matter when I'm the one selling?
Because your buyer can't close without it. The lender needs proof of homeowners coverage before it funds the loan, and a carrier has to agree to write your house first. If the best-priced carriers pass, the buyer either pays more or walks.
Kelsey Carlson, a Personal Lines Risk Advisor at Lemon Mohler Insurance, told me the Coast is in a much better spot than it was four or five years ago. Back then, carriers were dropping whole books of business. Today, she says problems are driven more by what an inspection finds at the specific house. That's good news for sellers, because inspection findings are things you can fix.
A higher premium also moves the buyer's payment. When insurance moves the payment, it can move the buyer's approval with it. That's how a clean inspection turns into a deal that falls through in week three.
What's the first fix that makes a house easier to insure?
The roof. Kelsey puts replacing an older roof at the top of her list, and it's the one that can stop a carrier from writing the house at all. I won't repeat the whole story here. Our post on roof age and your sale covers where carriers draw the line and what to do if replacing it isn't realistic.
If you are replacing it, look at a FORTIFIED roof before you sign a contract with a roofer. A FORTIFIED certificate is something you can hand a buyer, and buyers' agents know what it means.
Why do tree limbs over the roof matter to an insurance company?
Because limbs and roofs don't mix in a storm. Kelsey ranks keeping limbs clear of the roofline and the structure as her second fix. On the Coast, a big oak hanging over the house is a claim waiting for a windy afternoon.
This one's usually cheap compared to the roof. Hire a licensed tree service, trim anything touching or hanging over the roof, and pull limbs back from the siding. Keep the invoice. It goes in the folder you'll hand buyers.
Timing matters too. Do it before your listing photos, and ideally before hurricane season. If a named storm is in the Gulf while you're under contract, carriers can pause new coverage. You don't want a limb on the roof to be the thing a buyer's inspector writes up that week.
Does a messy yard really affect insurance?
Yes, and this one surprises people. Kelsey's third fix is keeping the yard clear of debris. Her most recent non-renewal was over yard debris. Once photos of the cleaned-up yard went to the carrier, it lifted the non-renewal.
Think about what that means for your buyer. Carriers often inspect the outside of a house after a new policy starts. Piles of lumber, old appliances, scrap metal, broken-down fencing and junk under the carport all show up in those photos.
Clearing it costs you a weekend and a trailer. Leaving it can cost your buyer a carrier. It also helps your listing photos, so it's the easiest fix on this list to justify.
What features make it harder for a buyer to get the best carrier?
This is where most sellers never look. Kelsey told me placement problems are often on the liability side, not the property side. A trampoline, a pool with a diving board or a slide, and certain dog breeds all narrow which carriers will write a policy. That can push a buyer off the better-priced carrier and onto a more expensive one.
The reason is liability. Insurers treat things like pools and trampolines as an attractive nuisance, meaning a feature that can draw in kids and lead to injuries. More ways to get hurt means more ways to get sued.
Some of this is easy for a seller. A freestanding trampoline leaves with you anyway, so take it down before photos. Your dog leaves with you too. The harder calls are features that stay with the house. A diving board or a pool slide conveys with the sale, and it narrows every buyer's carrier options, not just yours.
Don't pull them out on a guess. Some buyers love a slide. Before you list, have your agent and an insurance agent look at it together. A local agent can tell you whether it's costing you buyers or selling the house.
Should I fix these myself or give the buyer a credit?
Fix the cheap ones and document them. Tree trimming and yard cleanup cost far less than any credit a buyer will ask for after their inspector and insurer flag them.
The roof is the real decision. Sometimes a replacement pays for itself in a faster sale. Sometimes pricing the roof into the list price or offering a repair credit makes more sense. The wrong move is doing nothing and hoping nobody's carrier notices. Overpriced, under-maintained houses are exactly what drive up days on market on the Coast.
What paperwork should I have ready for buyers?
Put together a simple folder. Include the roof invoice or permit with the install date, any FORTIFIED certificate, and the tree service invoice. Add your current insurance declarations page and receipts for any storm repairs.
Buyers can take that folder straight to their agent and quote the address before they write. That's the whole goal. The fewer questions a carrier has, the faster your buyer gets a binder.
Anything you've repaired still belongs on your disclosure form. Here's what Mississippi sellers must disclose about storm damage. Documented repairs are the easiest part of that form to fill out well.
By the Numbers
3: Kelsey Carlson's ranked insurability fixes (roof, limbs, yard)
$10,000: maximum Strengthen Mississippi Homes FORTIFIED roof grant
4 to 5 years: how long ago carriers were dropping entire books of Coast business, per Kelsey
2026: first renewals mostly calm, from flat to a couple hundred dollars up, per Kelsey
The Bottom Line
On the Coast, your buyer has to sell your house to an insurance company before the sale is final. Fix the roof if it's older, trim the limbs, clear the yard, and take a hard look at the features that shrink a buyer's carrier options. Then put the paperwork in one folder. If you want to know what your house is worth before you start, get a free home value estimate. When you're ready, here's how we list and sell.
Frequently Asked Questions
What repairs should I make before selling a house on the Mississippi Gulf Coast?
Start with anything that affects insurance. A local insurance advisor ranks the top three as replacing an older roof, trimming tree limbs away from the roofline and structure, and clearing debris from the yard. Cosmetic updates come after those.
Can a trampoline or pool affect a buyer's insurance?
Yes. Trampolines, and pools with diving boards or slides, can narrow which carriers will write a policy because they raise liability risk. That can push a buyer to a more expensive carrier. A freestanding trampoline can simply leave with you.
Do overhanging tree limbs affect homeowners insurance?
They can. Limbs over the roof raise the risk of storm damage, and carriers look for them. Trimming limbs back from the roofline and the house is one of the cheapest fixes a Coast seller can make.
Is it better to replace the roof or give the buyer a credit?
It depends on the roof's age, your price point and your timeline. An older roof can stop some carriers from writing the house at all, so talk to your agent and an insurance agent before you list, not after an offer comes in.
Sources
Kelsey Carlson, CISR Elite, Personal Lines Risk Advisor, Lemon Mohler Insurance: ranked insurability fixes, liability features and carrier eligibility, inspection-driven non-renewals, yard debris example, 2026 renewal trends, interview September 2026
Progressive, What Is an Attractive Nuisance?: pools and trampolines as attractive nuisances and liability risk
Mississippi Insurance Department, Strengthen Mississippi Homes: FORTIFIED roof grant up to $10,000
About the Author
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He serves buyers and sellers across the Mississippi Gulf Coast.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!