Blog > What Is the Mississippi Wind Pool, and Do You Need It?
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Mississippi Gulf Coast home insurance guide.
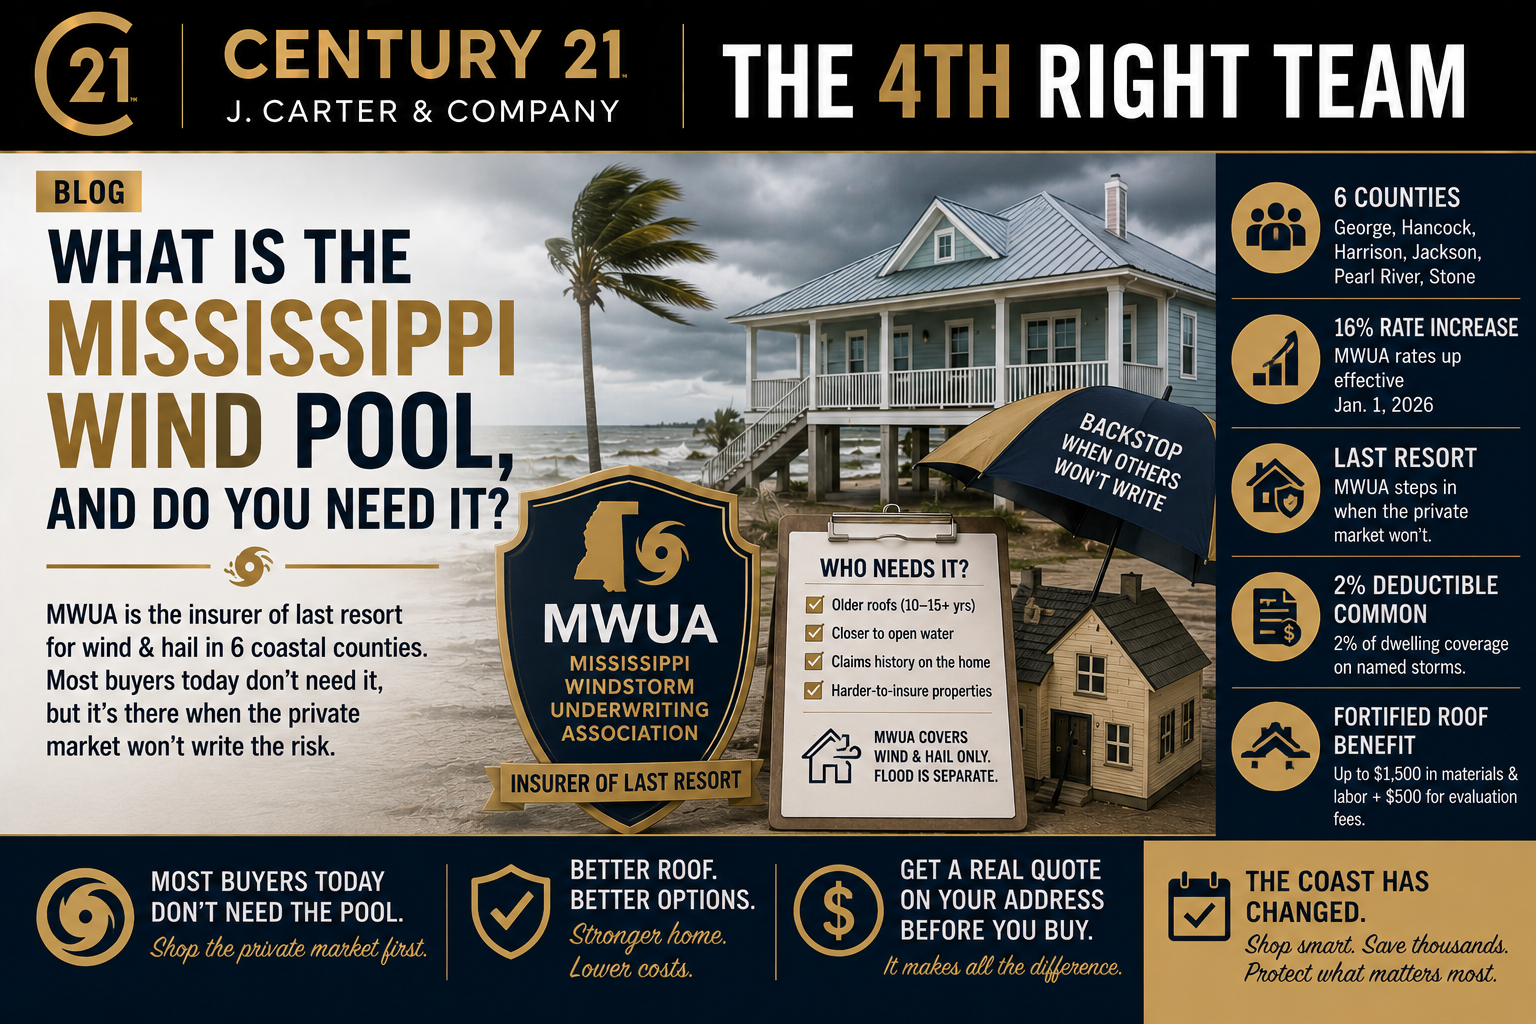
Quick Answer: The Mississippi wind pool is the Mississippi Windstorm Underwriting Association, or MWUA. It's a state-created insurer of last resort that sells wind and hail coverage only, in six coastal counties: George, Hancock, Harrison, Jackson, Pearl River, and Stone. Here's what changed. Most buyers on the Coast today don't end up in it, because nearly every homeowners carrier writing here now includes wind in the base policy. MWUA is the backstop for homes the private market won't touch, and MWUA rates rose 16% effective January 1, 2026.
If you're moving here from anywhere inland, somebody has already told you about the wind pool. They probably made it sound inevitable. It isn't. Not anymore.
What is the Mississippi Wind Pool?
MWUA provides windstorm and hail insurance in Mississippi's coastal area when the private market won't. The Legislature created it in 1987 through House Bill 274. Since 2007, it's run as an independent entity governed by its own board under state law.
It is not a tax-funded government program. It runs on premiums and on required assessments against property insurers licensed here. It's also not a full homeowners policy. It covers wind and hail. That's it.
It exists because hurricanes create losses no single insurer wants to carry alone. Before Katrina, MWUA had about 16,000 policies. Afterward, it grew to nearly 46,000 as carriers pulled back. Without the pool, a lot of Coast homes would be uninsurable, and uninsurable means unfinanceable. It's the reason a family in Waveland can still get a mortgage. Shrinking the pool is a stated goal, though, and right now that goal is working.
Do most Coast buyers actually end up in the Wind Pool?
No. And that's the part almost nothing online has caught up to.
I asked Kelsey Carlson, CISR Elite, a Personal Lines Risk Advisor at Lemon Mohler Insurance, how often she writes MWUA policies now. She told me she honestly couldn't tell you the last time. She very rarely sees a risk that doesn't fit with some other carrier, and nearly all of her homeowners carriers include wind. One offers a flat $500 wind deductible all the way down to the coast. When a home does need wind-only coverage, she said there are several private market options before the pool.
So the picture inland buyers get handed, three separate policies with the wind pool in the middle, describes the Coast of ten years ago. Today, most buyers land on one homeowners policy with wind included, plus flood if the property needs it. Flood is always separate. Wind usually isn't anymore. If you're wondering whether a home needs flood coverage, start with what a flood zone designation actually means.
Who still ends up in the Wind Pool?
Anyone in the six coastal counties who truly can't get wind coverage in the regular market. That's a real group, just a smaller one than it used to be.
Roof age is usually the reason. Some carriers won't write a roof over ten years old, and most start depreciating roof value around fifteen. After that, it's distance to open water, construction type, elevation, and the claims history on the address. Two houses on the same block can land differently. You can't apply on your own, either. MWUA works through a Mississippi licensed resident agent.
Timing matters too. When a named storm moves into the Gulf, the Wind Pool puts a no-bind moratorium in place. That means no new policies and no coverage increases until the storm passes. Here's what a named storm does to your closing.
Being in the pool isn't a mark against your house. It's a market condition, not a verdict on your property.
What does Wind Pool coverage do and not do?
It covers windstorm and hail damage to your structure and, depending on the policy, your contents. It does not cover flood. Nothing about a wind policy protects you from storm surge. That's a separate flood policy, and it's the most expensive misunderstanding on this Coast. Here's what flood coverage actually costs by zone.
Deductibles are commonly a percentage of coverage rather than a flat dollar amount. On a $250,000 dwelling, a 2% named storm deductible is $5,000 out of pocket before coverage kicks in. MWUA also caps coverage per location.
One truly good feature: if a covered claim replaces 50% or more of your roof, MWUA provides a FORTIFIED Roof endorsement at no cost. It reimburses up to $1,500 in materials and labor and $500 in evaluation fees toward the IBHS designation. That $500 matters more than it looks, because the state's FORTIFIED roof grant does not cover your evaluator fee.
What does the Wind Pool do to a monthly payment?
Less than you've been told, if you can stay out of it.
I can't give you a wind pool premium range, and I won't invent one. MWUA rates depend on dwelling value, deductible, construction, roof, and location. The spread is wide enough that any published average would mislead you. What I can tell you is that MWUA rates rose 16% on January 1, 2026, and the pool is built as a market of last resort, not a discount.
For scale, Insurify projected the Gulfport-Biloxi metro average at $7,459 a year by the end of 2026, against a Mississippi statewide average near $3,833. That's blended across every policy type in the metro. It's not a wind pool number. For the bigger picture, see what home insurance costs on the Coast.
Your real number comes from an independent local agent quoting your actual address, and that's why you get the quote before the offer. Ask whether wind can be included in the homeowners policy. If it can't, ask what private wind-only options exist before anyone mentions the pool.
How do you get out of the Wind Pool?
Roof first. A newer roof, especially a FORTIFIED Roof with an IBHS certificate, opens doors to credits and to private carriers who will take you back out of the pool. Mississippi also runs a grant paying up to $10,000 toward a FORTIFIED Roof retrofit through the Insurance Department.
Then shop it, and shop it again next year. What was pool-only three years ago is often writeable now.
One warning. MWUA operates under a fully earned premium rule. That means you generally can't get unearned premium back if you cancel mid-term, and premium financing usually doesn't work. Plan on paying in full or escrowing it.
By the Numbers
6 eligible counties: George, Hancock, Harrison, Jackson, Pearl River, Stone
16%: MWUA rate increase effective January 1, 2026
1987: the year the Legislature created the association, through House Bill 274
16,000: MWUA policies before Katrina, growing to nearly 46,000 after
$5,000: out of pocket on a 2% named storm deductible for a $250,000 dwelling
$1,500 plus $500: reimbursed under the MWUA FORTIFIED Roof endorsement
$10,000: maximum Strengthen Mississippi Homes grant toward a FORTIFIED Roof
The Bottom Line
The wind pool isn't something to be afraid of, and for most buyers today it isn't something you'll even use. It's the backstop that keeps coastal Mississippi financeable when a house won't fit anywhere else. Before you assume you're headed there, have a local independent agent shop your actual address. That one call is the difference between the Coast people warn you about and the Coast that's actually here. If you're just starting out, our buyer's guide puts the Coast-specific steps in order.
Frequently Asked Questions
What is the Mississippi wind pool?
It's the Mississippi Windstorm Underwriting Association, a state-created insurer of last resort providing wind and hail coverage in six coastal counties when private carriers won't write it. The Legislature created it in 1987.
Do I have to buy wind pool coverage if I move to the Mississippi Coast?
Usually no. Nearly every homeowners carrier writing on the Coast today includes wind and hail in the base policy. The wind pool is for homes the private market won't cover, usually because of roof age or location.
Which Mississippi counties can use the wind pool?
George, Hancock, Harrison, Jackson, Pearl River and Stone.
Does wind pool insurance cover flood damage?
No. Storm surge and rising water are flood, not wind. Flood stays separate even when wind is included in your homeowners policy.
Can I get out of the wind pool?
Sometimes, and more often than a few years ago. If a private carrier will write wind on your home, you can leave. A newer or FORTIFIED roof improves your odds, so have an independent agent re-shop it every year.
Sources
Mississippi Windstorm Underwriting Association overview (1987 creation, wind and hail only): https://msplans.com/node/6
MWUA Manual of Rules and Procedures (eligible counties, agent requirement, eligible property): https://msplans.com/sites/default/files/MWUA/Bulletins/MW_Rules_Procedures/mw%20manual%20of%20rules%20and%20procedures%20revisions%20effective%201-1-2016pdf.pdf
MWUA Plan of Operation (governance, deductibles, cancellation): https://msplans.com/sites/default/files/MWUA/Plan%20of%20Operation%202019%20final%20effective%207-1-19.pdf
MWUA named storm binding moratorium notices: https://www.msplans.com/node/335
Mississippi Insurance Department, Strengthen Mississippi Homes grant: https://www.mid.ms.gov/mississippi-insurance-department/preparedness/mitigation/smh/
Insurify 2026 Home Insurance Report, reported by the Sun Herald (Gulfport-Biloxi and statewide average premiums)
Kelsey Carlson, CISR Elite, Personal Lines Risk Advisor, Lemon Mohler Insurance (current carrier wind appetite and MWUA usage, September 2026)
Keep reading: Do You Need a Separate Wind Policy on the MS Gulf Coast? and How Much Is Home Insurance on the Mississippi Gulf Coast?
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com