Blog > Mississippi Gulf Coast Home Insurance: A 2026 Buyer's Guide
By Randy Richardson, Broker Associate, The 4th Right Team at Century 21 J. Carter & Company. Updated September 2026.
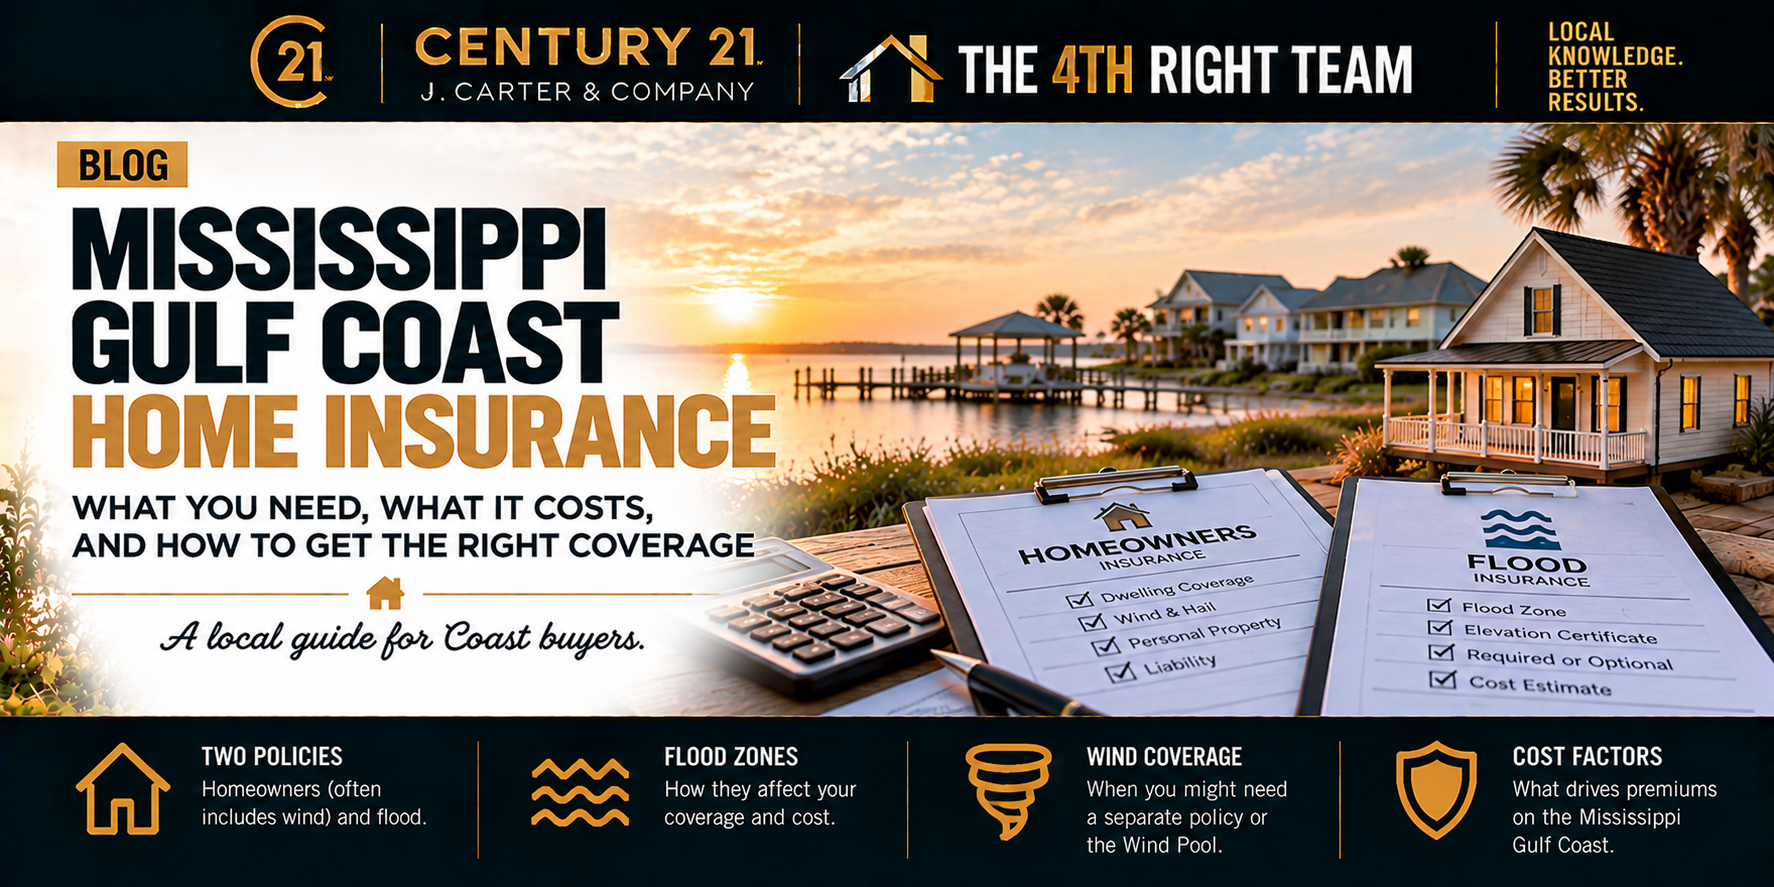
Quick Answer: Buying a home on the Mississippi Gulf Coast usually means two policies. The first is a homeowners policy, which on most Coast homes now includes wind and hail. The second is a separate flood policy, if the home needs one. If the home sits in a high-risk flood zone like AE or VE and your loan is federally backed, flood insurance is required. When private carriers won't cover wind on a home, usually because of roof age or location, the state Wind Pool covers wind and hail in six coastal counties. The smartest move is to get real quotes before you write an offer.
This guide is your starting point. Each section gives you the short answer, then links to our full post on that topic.
What insurance do you need to buy a home on the Mississippi Gulf Coast?
For most buyers today, it's two policies. A homeowners policy covers the house, your belongings, and liability. Most carriers writing on the Coast now include wind and hail in that policy. Flood is always separate. Standard homeowners policies don't cover flood anywhere in the country. Some homes still need separate wind coverage, usually because of an older roof or a spot close to open water. Your lender will want proof of coverage before closing. Together, these policies can move your monthly payment as much as your interest rate does.
How do flood zones and elevation certificates affect flood insurance?
Your flood zone tells your lender whether flood insurance is required. FEMA calls high-risk areas Special Flood Hazard Areas. On the map, they're zones that start with A or V, like AE and VE. If the home is in one and your loan is federally backed, you must carry flood insurance. Federal lending rules put the flood risk in these zones at 26% over a 30-year mortgage. Zone X is lower risk, and lenders usually don't require flood coverage there. Lower risk isn't no risk, though. You can look up any address on FEMA's Flood Map Service Center. Start with what a flood zone designation actually means, then see what AE vs. X costs you.
An elevation certificate shows how high a home sits compared to expected flood levels. It can help lower a flood quote, so ask for one before you write an offer. How the home is built matters too. Here's how slab, pier and beam, and pilings compare.
Do you need a separate wind policy on the Gulf Coast?
Usually not anymore. Kelsey Carlson, a Personal Lines Risk Advisor at Lemon Mohler Insurance, says nearly all of her homeowners carriers now include wind. A separate wind policy comes into play when a carrier won't cover wind on a specific home. An older roof is the most common reason. Private wind-only options come first. When those don't work, the Mississippi Windstorm Underwriting Association can step in. Most people call it the Wind Pool. It's the insurer of last resort for wind and hail in George, Hancock, Harrison, Jackson, Pearl River, and Stone counties. Read whether you need a separate wind policy and what the Mississippi Wind Pool is.
What drives the cost of home insurance on the Mississippi Gulf Coast?
There's no single Coast price. Two similar homes on the same street can get very different quotes. One local agent put the honest range for a $200,000 Gulfport home at $1,000 to $10,000 a year. The biggest factors are distance from the water, flood zone, elevation, roof age and type, and when the home was built. A home built to post-Katrina codes may quote differently than an older one. See how much home insurance costs on the Coast and how a pre-Katrina home compares to a post-2005 rebuild.
The roof matters more than most buyers expect. An older roof can limit which companies will write a policy. A FORTIFIED roof can earn a discount. Mississippi's Strengthen Mississippi Homes program offers grants of up to $10,000 toward a FORTIFIED roof. It's for owner-occupied, single-family primary homes. Read what roof age does to insurance and who qualifies for the $10,000 roof grant.
When should you get an insurance quote when buying a Coast home?
Get it before you write an offer, at the same time as your pre-approval. A surprise premium late in the deal can wreck your budget or even kill the sale. Here's why Coast buyers get the quote before the offer.
Timing matters during hurricane season too. When a named storm is in the Gulf, many insurers pause new policies until it passes. Each company sets its own rules. If your coverage isn't in place yet, your closing can slip. Read what a named storm does to your closing and use our hurricane season closing checklist.
One more timing rule. A new federal flood policy normally has a 30-day waiting period. That wait doesn't apply when you buy the policy for a loan closing, as long as you apply by closing day.
What should Gulf Coast sellers know about insurance?
Buyers will ask about the roof, flood history, and elevation. If you have those answers ready, you'll get fewer surprises during the deal. Gather your roof age records, any elevation certificate, and paperwork on past storm repairs before you list. Mississippi sellers also have duties to disclose past flooding and storm damage. See what Coast sellers should know about roof age and what you must disclose about flooding and storm damage.
By the Numbers
- 6: coastal counties in the Wind Pool's coverage area
- 1987: the year the Legislature created the Wind Pool
- 26%: chance of a flood over a 30-year mortgage in a high-risk zone
- 30 days: standard waiting period for a new federal flood policy, waived when bought for a loan closing
- $10,000: maximum Strengthen Mississippi Homes roof grant
- 5 years: how long a FORTIFIED designation lasts before re-inspection
- 17% to 20%: FORTIFIED roof discount range one inspector cited to WLOX (varies by insurer)
The Bottom Line
On the Coast, insurance isn't a box you check at the end. It's part of what the house really costs. Get quotes early, ask for the elevation certificate, and know the roof's age before you fall in love with a home. If you want a second set of eyes on a specific house, we're glad to walk through it with you.
Frequently Asked Questions
Is flood insurance required on the Mississippi Gulf Coast?
It's required if the home is in a high-risk flood zone, like AE or VE, and your loan is federally backed. Lenders can require it in other zones too. Many owners outside high-risk zones buy it anyway.
Does homeowners insurance cover hurricane damage on the Coast?
Wind damage, usually yes. Most Coast carriers now include wind and hail in the homeowners policy, though some homes still need separate wind coverage. Flooding and storm surge are never covered by homeowners insurance. You need a flood policy for that.
What is the Mississippi Wind Pool?
The Wind Pool is the Mississippi Windstorm Underwriting Association. It sells wind and hail coverage to homeowners in six coastal counties who can't get it from private insurers. It doesn't cover anything except wind and hail.
How long does flood insurance take to start?
A new federal flood policy usually takes 30 days to start. If you buy it for a loan closing and apply by closing day, coverage can start at closing.
Can I get a grant for a stronger roof in Mississippi?
Yes. The Strengthen Mississippi Homes program offers up to $10,000 toward a FORTIFIED roof. It's for owner-occupied, single-family primary homes, and awards are made by lottery. Check the Mississippi Insurance Department's site for when applications open.
Sources
- Mississippi Windstorm Underwriting Association, Manual of Rules and Procedures: Wind Pool coverage area and eligibility
- Mississippi Windstorm Underwriting Association overview: 1987 creation, wind and hail only
- Mississippi Insurance Department, Strengthen Mississippi Homes: $10,000 grant, eligibility, 5-year designation
- WLOX, April 7, 2026: lottery system and inspector's discount estimate
- FEMA NFIP Bulletin W-09065: flood policy waiting period exception at loan closing
- 12 CFR Part 339, Appendix A: mandatory flood insurance and 26% risk figure
- FEMA Flood Map Service Center: flood zone lookup by address
- Kelsey Carlson, CISR Elite, Personal Lines Risk Advisor, Lemon Mohler Insurance: carrier wind appetite and premium range, September 2026
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!