Blog > Your Home Insurance Carrier Non-Renewed You. Now What?
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Mississippi Gulf Coast home insurance guide.
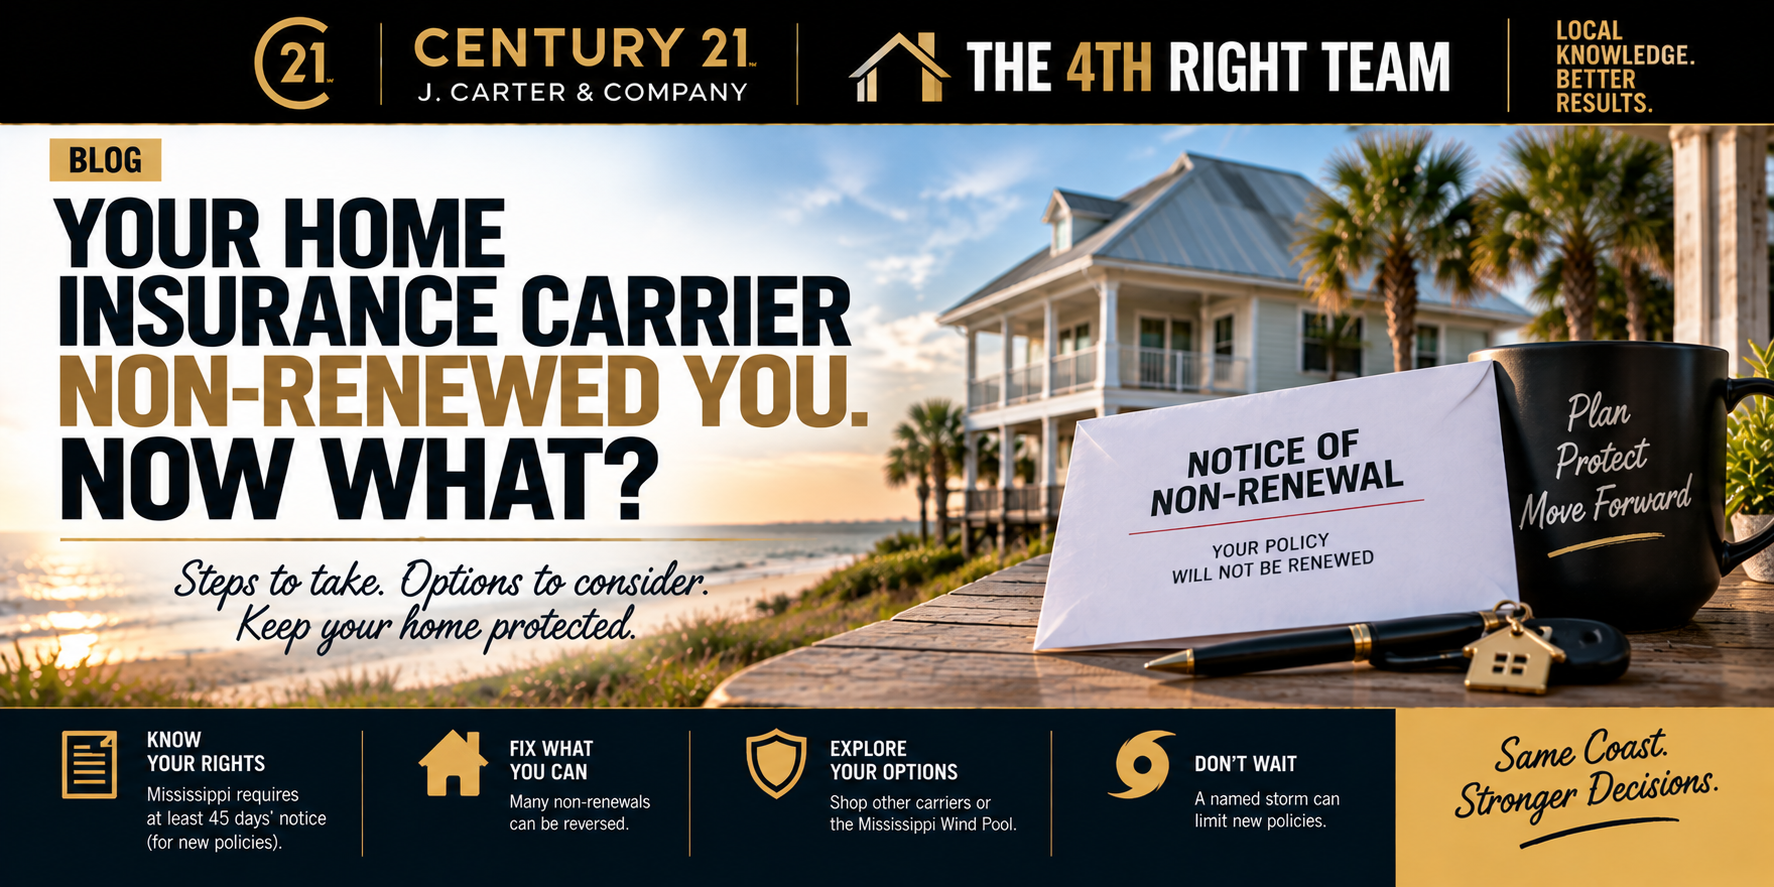
Quick Answer: If your homeowners carrier sends a non-renewal letter on the Mississippi Gulf Coast, call your insurance agent the day it arrives. For policies issued or renewed on or after July 1, 2026, Mississippi law requires at least 45 days' written notice to you and to your mortgage lender, up from 30. Today, most Coast non-renewals come from inspection findings like yard debris, overhanging limbs, or an aging roof. Many can be reversed by fixing the problem and sending photos. The costly mistakes are waiting until the last week, when a storm in the Gulf can stop carriers from writing new policies, or missing the letter because the policy is paid from escrow.
Why do carriers non-renew homes on the Mississippi Gulf Coast?
These days, it's usually about your house, not the whole Coast. That's a real change from a few years ago.
Kelsey Carlson, CISR Elite, a Personal Lines Risk Advisor at Lemon Mohler Insurance, told me the Coast is in a much better spot than it was four or five years ago. Back then, carriers were non-renewing entire books of business. Now, she said, most non-renewals come from what an inspector finds at the property.
Those findings tend to be ordinary things. An older roof is the big one, and roof age can knock a house out of a carrier's appetite no matter how well it's kept. Tree limbs over the roofline, debris in the yard, and liability issues like a trampoline or a pool with a diving board or slide can do it too.
Mississippi law gives you some protection on the roof question. Since July 2024, once an insurer has issued a policy or a binder on your home, it can't cancel that policy or binder, or deny coverage, solely because of the roof's age. The law's wording doesn't mention non-renewal, though. So a carrier may still decline to renew over an older roof, even though it can't cancel you mid-term for that reason alone.
How much notice does Mississippi require before a non-renewal?
At least 45 days, for policies issued or renewed on or after July 1, 2026. Before that, the rule was 30 days. The change came from House Bill 1611 in the 2025 session, which amended Mississippi Code section 83-5-28.
The notice has to go to you and to any creditor named on the policy, which usually means your mortgage lender. If the carrier misses the notice requirement, the law lets you keep the policy at your existing premium for the rest of the notice period plus another 45 days. That keeps rolling in 45-day steps until proper notice is given.
The same 45-day notice applies when a carrier reduces your coverage, and Mississippi counts a higher deductible as a reduction. A premium increase by itself doesn't count. If your renewal shows up with a bigger deductible and no advance notice, ask your agent about it.
One timing detail matters here. The 45-day rule applies to coverage issued or renewed on or after July 1, 2026. If your policy last renewed before that date, ask your agent which notice period applies to your current term.
Also know what doesn't count as a non-renewal. If your carrier moves you to an affiliated company in the same insurance group with substantially similar coverage, the law treats that as a renewal. You should still get notice of any less favorable terms and the new company's financial rating.
What should I do the day the non-renewal letter arrives?
Call your agent that day. Kelsey said Lemon Mohler is often already working on a client's non-renewal before the client even calls, but don't count on that from every office.
Then read the reason on the letter. If it's something you can fix, fix it and document it. Kelsey's most recent non-renewal was over yard debris. Once photos of the cleaned-up yard went in, the carrier lifted it. Trimming limbs back from the roof works the same way.
If the reason is the roof, the fix is bigger, but it's still a fix. A new roof can also open the door to discounts, and the Strengthen Mississippi Homes program can help with the cost of a FORTIFIED roof if you qualify.
If the carrier won't budge, your agent shops the house to other companies. That's where knowing what your current policy covers matters. Most Coast carriers now include wind and hail in the base policy, though some still exclude it and need separate wind coverage. If you can't find wind coverage in the private market, the Wind Pool is the backstop.
Why is waiting until the last minute so risky on the Coast?
Because the Gulf doesn't wait for your renewal date. When a storm reaches a certain point in the Gulf, carriers stop binding new policies until it passes. Kelsey said those triggers vary by carrier, and most are tied to a storm reaching set coordinates, not a forecast cone. Here's more on what a named storm does to coverage and closings.
So if your policy ends in September and you start shopping the last week of August, one named storm can leave you with no carrier willing to write a new policy on the day your old one ends. Forty-five days sounds like plenty. During hurricane season, it can go fast.
What happens if my policy is paid through escrow?
This is the one that catches people. Kelsey said a costly mistake she sees is homeowners who don't know about the non-renewal at all, because the policy is paid from escrow and they assume it's on autopilot.
Your lender gets a copy of the notice, but that doesn't mean they'll find you a new policy. If your coverage lapses, federal rules let the loan servicer buy force-placed insurance and charge it to you, after sending required notices. Force-placed coverage usually costs more, and it's built to protect the lender's interest, not yours. Open every letter from your insurance company, even when your lender pays the bill.
If you're buying, the same logic applies in reverse. Get an insurance quote before you write an offer, because you need a bound policy to close, and you want to know the house is insurable first.
How do I keep a non-renewal from happening again?
Kelsey's list for a house that's easier to insure is short. Replace an older roof. Keep limbs trimmed back from the roofline and the structure. Keep the yard clear of debris. And think about how liability items like a trampoline or a certain dog breed can narrow which carriers will write you.
Those same fixes matter when you sell. A buyer's carrier will look at the same things, and a house that's hard to insure is harder to sell. If a non-renewal is the reason you're thinking about moving, start with a home value evaluation so you know your options.
By the Numbers
Mississippi non-renewal notice for policies issued or renewed on or after July 1, 2026: 45 days
Previous notice requirement: 30 days
Notice for non-payment when a lender is named on the policy: 10 days
Extension if the carrier misses the notice rule: the remainder of the notice period plus 45 days, at the existing premium
Law behind the change: House Bill 1611, 2025 Regular Session, amending Mississippi Code 83-5-28
Roof age protection: since July 1, 2024, no cancellation of a policy or binder solely because of roof age (SB 2130)
Atlantic hurricane season: June 1 to November 30
The Bottom Line
A non-renewal letter isn't the end of your coverage. It's a deadline. Call your agent the day it comes, fix what you can and document it, and start shopping early enough that a storm in the Gulf can't box you in. If the house needs work to stay insurable, it'll need that same work when you sell.
If you want to talk through what a non-renewal means for your home's value or your next move, a local agent can help you sort it out. That's what my team does every day.
Frequently Asked Questions
How much notice does an insurance company have to give before non-renewing a home in Mississippi?
At least 45 days for policies issued or renewed on or after July 1, 2026, sent to you and to any lender named on the policy. Before that date, the requirement was 30 days.
Can a non-renewal be reversed?
Often, when it's based on an inspection finding. Fix the issue, like yard debris or overhanging limbs, send photos through your agent, and ask the carrier to reconsider.
What if I can't find a new policy before my current one ends?
Work with your agent early, because carriers can stop binding new policies when a storm is in the Gulf. If private carriers won't write wind coverage, the Mississippi wind pool is the backstop for wind in the coastal counties.
What happens if my escrowed insurance lapses?
Your loan servicer can buy force-placed insurance and charge you for it after sending required notices. It usually costs more and mainly protects the lender.
Sources
45-day notice, lender notice, 45-day extension if notice is missed, affiliate transfers: Mississippi House Bill 1611, 2025 Regular Session, as sent to the Governor
Prior 30-day rule: Mississippi Code section 83-5-28 (Justia)
Mississippi Insurance Department guidance on HB 1611, Bulletin 2025-5 (summary): https://www.resourcepro.com/?p=29052
Roof age protection: Mississippi Senate Bill 2130, 2024 Regular Session, as sent to the Governor: https://billstatus.ls.state.ms.us/documents/2024/pdf/SB/2100-2199/SB2130SG.pdf
Force-placed insurance rules: CFPB Regulation X, 12 CFR 1024.37: https://www.ecfr.gov/current/title-12/chapter-X/part-1024/subpart-C/section-1024.37
Atlantic hurricane season dates: NOAA National Hurricane Center
Non-renewal causes, reversals, binding moratorium triggers and escrow mistakes: Kelsey Carlson, CISR Elite, Personal Lines Risk Advisor, Lemon Mohler Insurance, written answers, September 2026
Keep reading: Roof Age and Insurance: What Coast Sellers Must Know and Named Storm in the Gulf? What It Does to Your Closing
About the Author
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He serves buyers and sellers across the Mississippi Gulf Coast.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!