Blog > Hurricane Season Closing Checklist for Mississippi Gulf Coast Buyers and Sellers
Hurricane Season Closing Checklist for Mississippi Gulf Coast Buyers and Sellers
by
Hurricane Season Closing Checklist for Mississippi Gulf Coast Buyers and Sellers
By Randy Richardson, Broker Associate, The 4th Right Team
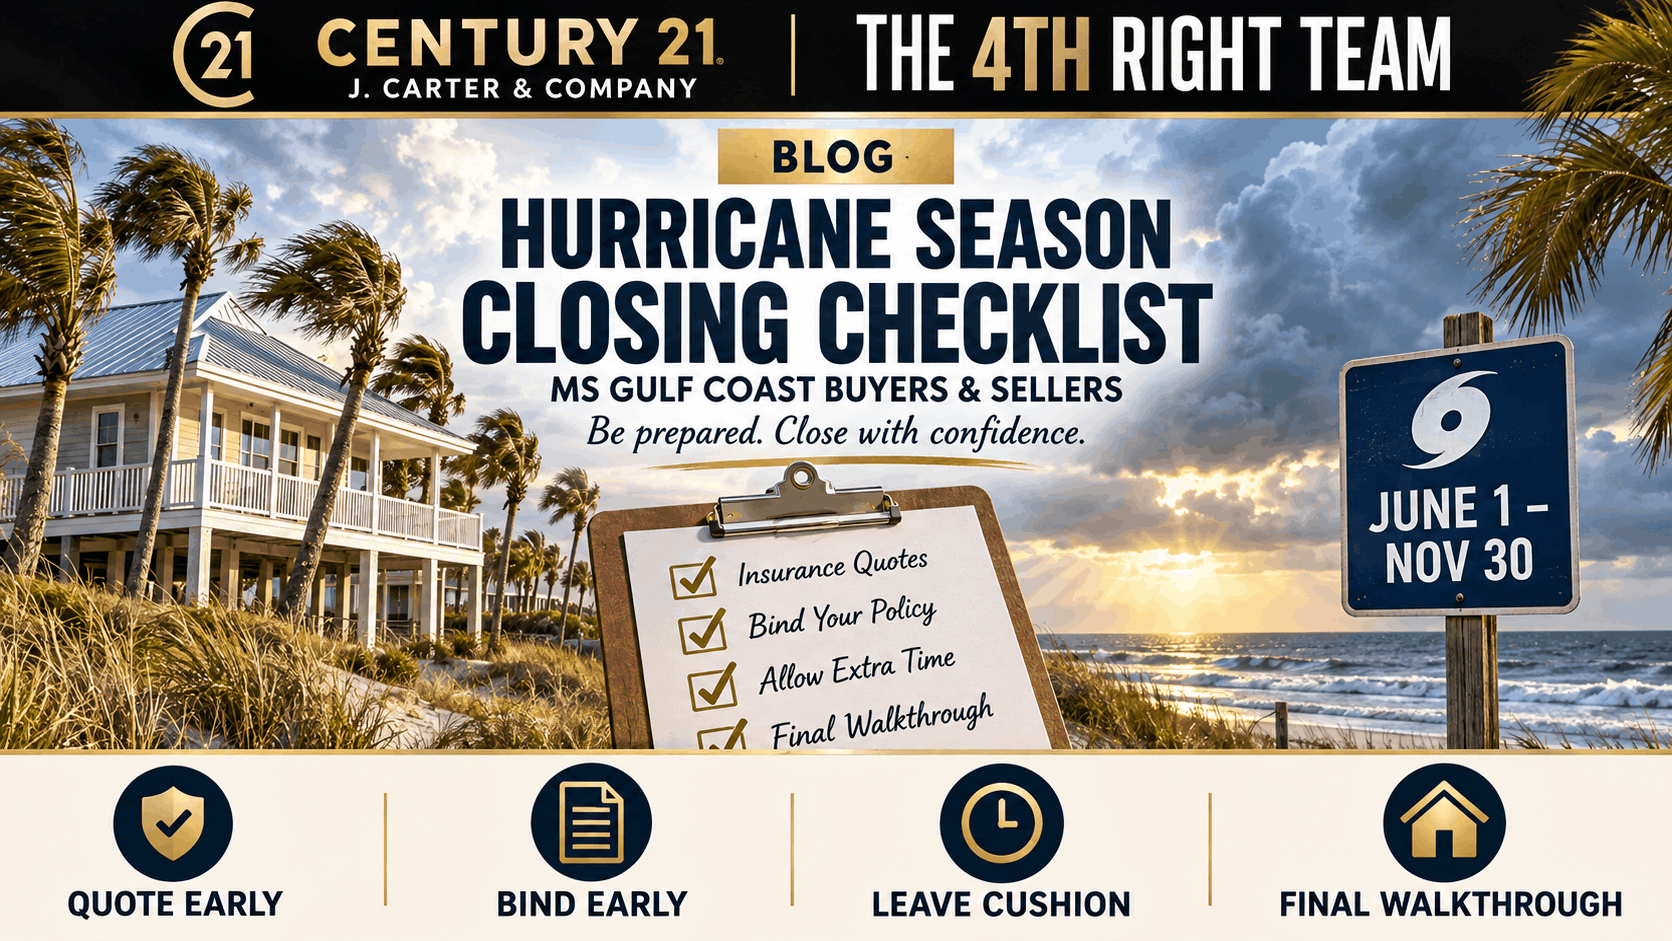
Quick Answer: Hurricane season on the Mississippi Gulf Coast runs June 1 through November 30, and a storm can delay a closing even if it never comes ashore here. The fix is timing. Buyers should get insurance quotes before writing an offer, bind policies the first week under contract, and leave a few spare days in the closing date. Mississippi's standard REALTORS® contract keeps the risk of loss on the seller until title transfers, so sellers need to keep their coverage in force through closing. If a storm does hit, expect the lender to confirm the home's condition before the loan funds.
I've already written about why a named storm can stall a closing. This post is the to-do list. It's built for anyone buying or selling between June and November, and it's worth a screenshot.
What should buyers do before writing an offer during hurricane season?
Get pre-approved first. A storm can squeeze your timeline later, so you don't want financing to be the slow part. Start with a solid pre-approval before you tour seriously.
Quote the insurance on the address. On the Coast, insurance can make or break the monthly payment. Get an insurance quote before you write the offer, not after you're under contract.
Ask about the roof and the year built. Carriers look hard at roof age, and an older roof can stop a policy cold. If the home was built before Katrina, read up on the pre-Katrina home vs. post-2005 rebuild differences first.
Ask for the elevation certificate. If the home sits in a flood zone, the elevation certificate tells you a lot about what flood coverage will cost. That goes double for waterfront homes.
Build cushion into the closing date. Between June and November, I don't like writing a closing date with zero wiggle room. A few spare days can save the whole deal if a storm pops up the week you're supposed to sign.
What should you do the first week under contract?
Bind your homeowners policy. Don't just collect quotes. Bind the policy with an effective date that matches your closing day. A policy that's already bound stays in force if a storm forms later. Make sure you understand your wind coverage and your wind deductible before you sign anything.
Line up flood insurance if your lender requires it. Most NFIP flood policies have a 30-day waiting period. When the policy is bought in connection with a loan closing, that wait doesn't apply. Flood coverage is always a separate policy, so don't assume your homeowners policy covers it.
Watch the NFIP deadline if you're closing late in the year. As of September 2026, Congress has authorized the National Flood Insurance Program only through December 11, 2026. If that authority lapses, the NFIP can't write new policies until Congress acts. If your closing lands near that date, ask your insurance agent about taking over the seller's existing NFIP policy or getting a private flood quote as a backup.
Send the paperwork right away. Get your insurance binder to your lender and closing attorney the day you have it. Then schedule your home inspection early, so you're not waiting on a report while a storm is spinning in the Gulf.
What should you do when a storm forms in the Gulf before closing?
Don't panic, and call your agent. If your policy is already bound, you're in good shape. If it isn't, most carriers won't write new coverage until the storm passes, and Mississippi's wind pool follows the same kind of freeze.
Put any extension in writing. If the closing date is going to slip, get a signed extension before the date passes. A handshake isn't enough when a contract deadline is on the line.
Plan for evacuation. If there's a chance you'll leave town, ask your closing attorney now whether you can sign early or sign from wherever you'll be. Keep your ID, contract, and loan documents saved on your phone.
Guard against wire fraud. Scammers love chaos. Never wire closing funds based on an emailed instruction, even one that looks right. Call your closing attorney's office at a number you already have and confirm every detail by voice.
What happens if a hurricane damages the house before closing?
The seller carries the risk until title transfers. Mississippi's standard REALTORS® purchase contract puts the risk of loss from fire or other casualty on the seller until title is conveyed. What happens next, whether that's repairs, a new price, or walking away, depends on the rest of your contract. That's a conversation for your agent and closing attorney, not a guessing game.
Walk the house again. Even if the storm looked like a miss, check the roof, ceilings, windows, and yard. Take dated photos of anything that changed since your inspection.
Expect your lender to check, too. Fannie Mae's guidelines say a lender has to take reasonable steps to find out whether a home's condition changed after a disaster. The lender decides whether a re-inspection or a new appraisal is needed. Either one can add days, so build that into your plans.
Do your final walkthrough last. Schedule it as close to closing as you can. After any storm, it's your best chance to catch new damage before the house is yours.
What should sellers do to protect a closing during hurricane season?
Keep your insurance until the sale funds. Since the risk of loss stays with you until title transfers, don't cancel your homeowners or flood policy early. Cancel it after closing, not before.
Document the house before a storm. Take a quick, dated video of every room, the roof, and the exterior. If something happens, that video makes the insurance claim and the conversation with the buyer much easier.
Secure the property. If you've already moved out, line up someone to put up shutters, bring in yard furniture, and check the house after the storm. An empty house with a small roof leak can turn into a big problem in a week.
Tell your agent about any damage right away. Don't wait for the buyer to find it at the walkthrough. Getting ahead of it keeps trust in the deal and gives everyone time to work out a fix. Sometimes that's where a local agent can save a closing that looks shaky.
By the Numbers
Atlantic hurricane season: June 1 through November 30
Typical peak of storm activity: August through October
Standard NFIP flood policy waiting period: 30 days
NFIP waiting period when bought for a loan closing: none
NFIP authorized through, as of September 2026: December 11, 2026
Who carries the risk of loss under Mississippi's standard REALTORS® contract: the seller, until title transfers
The Bottom Line
You don't need to avoid buying or selling during hurricane season. You just need to do things in the right order. Sellers, keep your coverage in place and document the house, and if you're thinking about listing, here's how I sell homes on the Coast. Buyers, quote early, bind early, and give your closing date room to breathe. My buyer's guide walks you through the rest.
Frequently Asked Questions
Can a hurricane cancel a home closing in Mississippi?
Usually, a storm delays a closing rather than cancels it. The deal stays alive, but you may need a written extension. If the storm damages the house, the rest of your contract decides what happens next.
Who pays if a hurricane damages the house before closing in Mississippi?
Mississippi's standard REALTORS® contract puts the risk of loss from fire or other casualty on the seller until title transfers. Your own contract controls, so ask your closing attorney how it applies to your deal.
Do I need a new appraisal if a hurricane hits before closing?
Maybe. Your lender has to check whether the home's condition changed after the storm. The lender decides whether a re-inspection or a new appraisal is required.
Can I get flood insurance right before closing?
Yes. An NFIP flood policy bought in connection with a loan closing skips the usual 30-day wait. As of September 2026, the NFIP is authorized through December 11, 2026, so late-year buyers should line up flood coverage early.
Sources
NOAA, 2026 Atlantic hurricane season outlook update (August 6, 2026). Season dates: https://www.noaa.gov/news-release/noaa-maintains-prediction-for-below-normal-atlantic-hurricane-season
CBS News, NOAA 2026 hurricane outlook coverage (May 21, 2026). August through October peak: https://www.cbsnews.com/news/2026-atlantic-hurricane-season-outlook-noaa-forecast/
Mississippi contract for the sale and purchase of real estate, risk of loss clause: https://bradley-law.com/wp-content/uploads/2025/12/Mississippi-Real-Estate-Contract-Form.pdf
Fannie Mae Selling Guide B2-3-05, Properties Affected by a Disaster. Lender duty to confirm property condition: https://selling-guide.fanniemae.com/sel/b2-3-05/properties-affected-disaster
Florida Department of Financial Services, Flood Insurance Coverage FAQs. NFIP 30-day waiting period and loan closing exception: https://www.myfloridacfo.com/division/consumers/storm/flood-disaster-faqs
NAHB, National Flood Insurance Program Extended Through Dec. 11 (September 2026): https://www.nahb.org/blog/2026/09/nfip-extension
Congressional Research Service, What Happens If the NFIP Lapses? Current authorization date and lapse effects: https://www.congress.gov/crs-product/IN10835
About the Author
I'm Randy Richardson, Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. I help buyers and sellers across the Mississippi Gulf Coast make smart moves, from the first showing to the closing table.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!