Blog > Your Insurance Check Is Made Out to Your Lender Too: Getting Paid After a Storm
Your Insurance Check Is Made Out to Your Lender Too: Getting Paid After a Storm
by
Your Insurance Check Is Made Out to Your Lender Too: Getting Paid After a Storm
By Randy Richardson, Broker Associate, The 4th Right Team
This post is part of our Mississippi Gulf Coast home insurance guide.
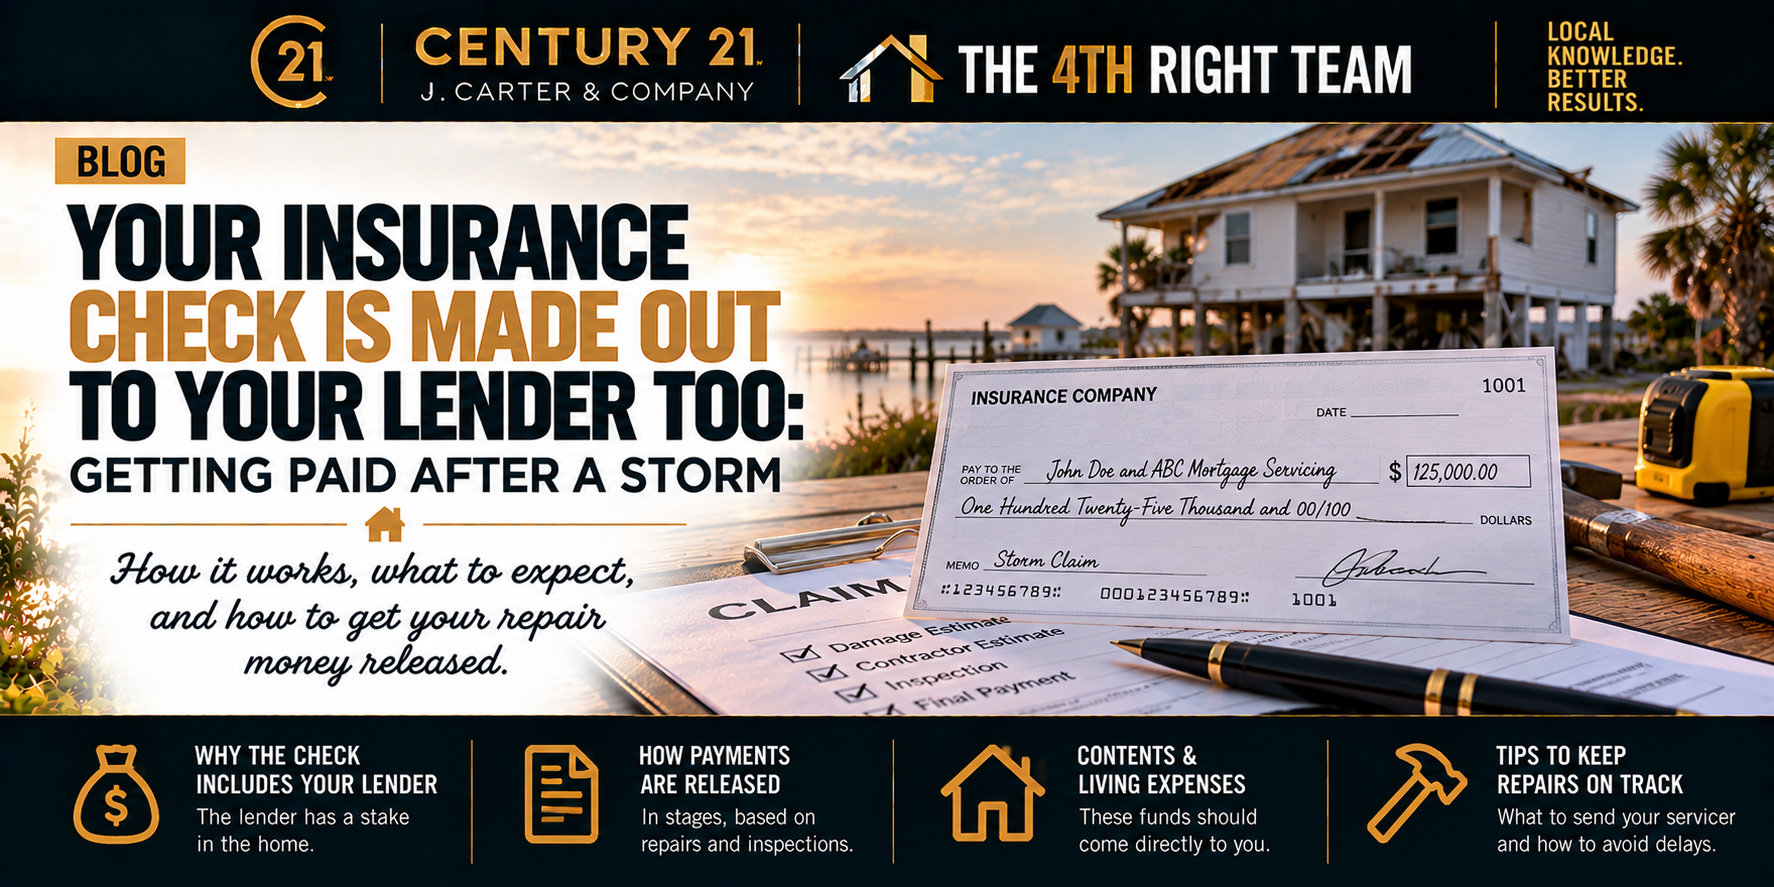
Quick Answer: If you have a mortgage, your homeowners insurance check after a hurricane will usually be made out to both you and your mortgage servicer. You can't cash it alone. You endorse it and send it to the servicer's loss draft department, which holds the money and releases it in stages as repairs get done. For loans owned by Fannie Mae that are current, the servicer can release up to $40,000 or 33% of the claim, whichever is greater, before work starts. The rest follows inspections. Money for your belongings and living expenses should come straight to you.
After every big storm on the Coast, I hear the same surprise from homeowners. The adjuster finally paid, the check came in the mail, and they couldn't deposit it. Here's why, and how to get the money moving.
Why is my insurance check made out to my mortgage company?
Because the lender has a stake in the house. Your mortgage requires you to insure the home, and the lender is listed on the policy as the mortgagee. So the Consumer Financial Protection Bureau says insurers generally pay a settlement with a check made out to both you and your servicer.
That applies to the dwelling part of the claim, the money meant to repair or rebuild the house. It applies to wind claims and to flood claims alike. The servicer's job is to make sure the money goes into the house that secures the loan.
How does the servicer release the money?
In stages. The CFPB describes the usual pattern: part of the money before work starts, more as work progresses and the rest after the job is finished and the home passes inspection.
Fannie Mae's servicing guide spells out its version for loans it owns. If your loan is current or less than 31 days late, the servicer may release an initial payment of up to the greater of $40,000 or 33% of the insurance proceeds. The rest goes out based on repair inspections, after the servicer reviews your final repair plans. Undisbursed money has to sit in an interest-bearing custodial account.
If your loan is 31 or more days behind, the rules tighten. Claims of $5,000 or less can still go out in one payment. Larger claims start with 25% of the proceeds, but no more than $10,000, with more released after inspections.
FHA, VA, Freddie Mac and portfolio loans each have their own rules. Your servicer can tell you which ones apply to yours.
What about money for my belongings and a place to stay?
That should come to you. Fannie Mae's guide tells servicers to immediately issue the borrower a check for any proceeds designated for contents or living expenses. If your check lumps everything together, ask the adjuster to break it out by coverage. Then ask the servicer to release the contents and living expense portion right away.
That money is what keeps your family in a hotel or rental while the house is being fixed. Don't let it get stuck in the repair queue.
What do I send the servicer to get my repair money?
Start with a phone call to the servicer's loss draft or insurance claims department, not general customer service. Ask for their packet and a direct contact. Each servicer has its own forms, but common requests include:
The endorsed insurance check, signed by everyone named on it
The adjuster's estimate or proof of loss showing what was paid and for what
A signed contract and estimate from your contractor
The contractor's license, insurance and tax information
Lien waivers as payments go out
Keep copies of everything, and track every call with the name, date and what was promised. United Policyholders, a national consumer group, recommends exactly that, along with written follow-ups when things stall.
How do I keep my contractor paid while the money's held?
Line up the schedule before work starts. Share the servicer's release schedule with your contractor, so their payment milestones match the inspection milestones. A contractor who expects half up front when the servicer only releases a third is a contractor who walks off the job.
Request each inspection as soon as a stage is done. Delays usually come from paperwork sitting in a queue, not from the servicer refusing to pay. And be wary of anyone asking for a large deposit before the servicer's first release clears. That's a red flag after any storm.
What if the damage is major and my home is in a flood zone?
Then there's one more rule to know. If a home in a high-risk flood zone is substantially damaged, generally meaning repairs cost 50% or more of its market value, local floodplain rules can require it to be brought up to current standards, often by elevating it. The local floodplain administrator makes that call.
If you carry NFIP flood insurance, Increased Cost of Compliance coverage can pay up to $30,000 toward that work. Ask your adjuster about it early. It's part of why a pre-Katrina home and a post-2005 rebuild can fare so differently after the same storm.
If the roof is being replaced anyway, look at building it to the FORTIFIED standard. Here's how the Strengthen Mississippi Homes grant works.
Do I still have to pay my mortgage after a storm?
Yes. The CFPB is clear on this: you still owe your mortgage after a disaster. If a storm makes it hard to pay, call your servicer right away and ask about forbearance or other options before you fall behind. Falling behind can also tighten how your claim money gets released.
If you're under contract to buy or sell when a storm hits, that's a different set of problems. Here's what a named storm does to a closing, and our hurricane season checklist.
By the Numbers
2: names usually on a dwelling claim check, yours and your servicer's
$40,000 or 33%: greater of the two, the initial release Fannie Mae allows on current loans
31 days: delinquency point where Fannie Mae's release rules tighten
$5,000: claims Fannie Mae allows paid in one payment even on delinquent loans
50%: common substantial damage threshold that can trigger rebuilding to current flood rules
$30,000: maximum NFIP Increased Cost of Compliance coverage
November 30: last day of hurricane season
The Bottom Line
Your claim check isn't stuck. It's just routed through your servicer. Call the loss draft department the day the check arrives, send the paperwork they ask for, match your contractor's schedule to theirs and keep paying your mortgage. If a storm leaves you deciding whether to repair or sell, start with a free home value estimate, and a local agent can walk you through both paths.
Frequently Asked Questions
Why is my homeowners insurance check made out to my mortgage company?
Because your lender is listed on your policy as the mortgagee and has a stake in the home. Insurers generally make dwelling claim checks payable to both you and your servicer, and the servicer releases the money as repairs are done.
How long does a mortgage company hold insurance money?
Until repairs are done and inspected. The money is typically released in stages. For current Fannie Mae loans, the servicer can release up to the greater of $40,000 or 33% of the proceeds up front, with the rest tied to inspections.
Does my mortgage company get my contents and living expense money too?
It shouldn't hold it. Fannie Mae's servicing guide tells servicers to immediately release proceeds designated for contents or living expenses to the borrower. Ask your adjuster to break the payment out by coverage.
What if my home is substantially damaged in a flood zone?
Local floodplain rules can require it to be brought up to current standards, often by elevating it. NFIP flood policies include Increased Cost of Compliance coverage of up to $30,000 toward that work.
Sources
Consumer Financial Protection Bureau, How do home insurance companies pay out claims?: checks payable to homeowner and servicer, staged releases, final inspection
Consumer Financial Protection Bureau, What do I do if my house was damaged or destroyed after a disaster?: continuing mortgage payments, contacting the servicer, forbearance
Fannie Mae Servicing Guide B-5-01, Insured Loss Events: $40,000 or 33% initial release, delinquent loan rules, contents and living expense proceeds, interest-bearing custodial account
United Policyholders, Let Go Lender: progress payments and documenting servicer contacts
FEMA, Increased Cost of Compliance: substantial damage and up to $30,000 toward bringing a flood-damaged home into compliance
About the Author
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He serves buyers and sellers across the Mississippi Gulf Coast.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
📞 Office: (228) 731-3881 | Cell: (228) 547-9999
📧 realtorrandyrichardson@gmail.com
🌐 www.The4thRightTeam.com
Looking to SELL or BUY? I know a GUY!