Blog > Manufactured Homes on Land: The One Question That Decides Everything
Manufactured Homes on Land: The One Question That Decides Everything
By Randy Richardson, Broker Associate, The 4th Right Team
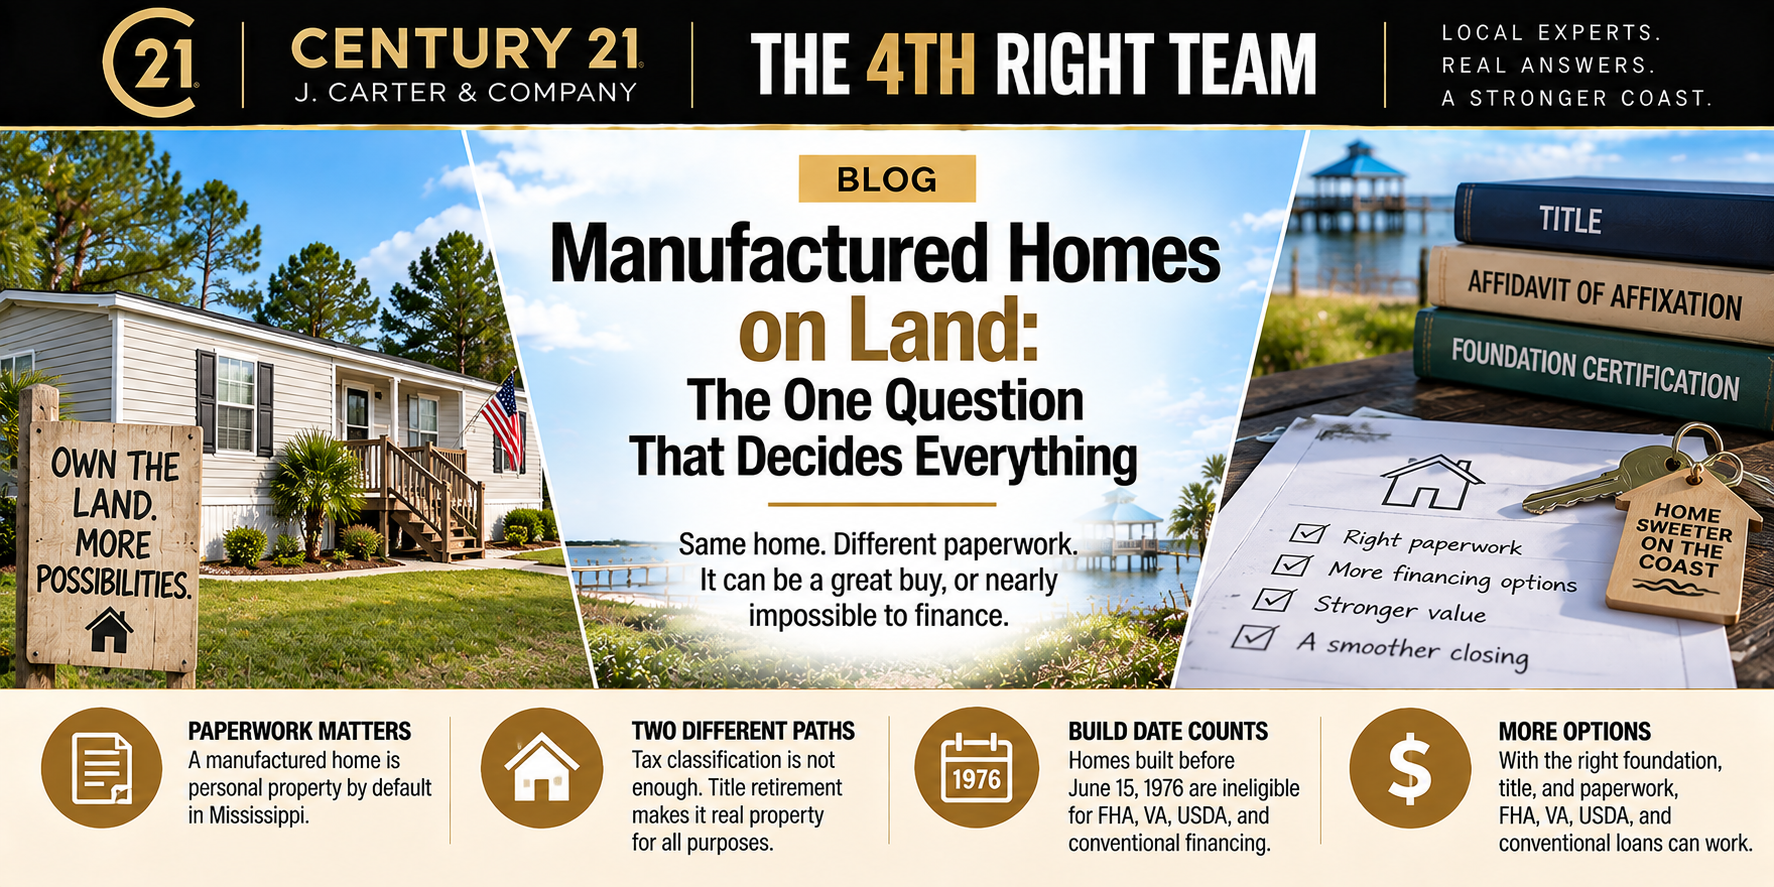
Quick Answer: A manufactured home sitting on land you own can be a great buy on the Mississippi Gulf Coast, or it can be nearly impossible to finance, and the difference comes down to paperwork. Under Mississippi law, a manufactured home is personal property by default. It stays that way, titled like a vehicle, unless the owner takes specific steps to change it. Mississippi actually has two different paths, and only one of them makes the home real property for all purposes. That's title retirement under Section 63-21-30, which requires cancelling the certificate of title and recording an affidavit of affixation in the land records. The other path only reclassifies it for property tax purposes. Lenders care about the first one. Build date matters too. Homes built before June 15, 1976 are permanently ineligible for FHA, VA, USDA, Fannie, and Freddie financing.
Personal property or real property
Everything flows from this. A site-built house is real property the second it's finished. A manufactured home isn't. Mississippi Code Section 27-53-15 says manufactured and mobile homes are personal property unless the owner, who also owns the land, takes action to change that.
If it's still personal property, it's titled through the state like a car. You finance it with a chattel loan, which typically means a higher rate and a shorter term, usually 15 to 20 years. You don't get mortgage rates and you don't get most mortgage programs.
If it's been converted properly, it's part of the land. It gets a mortgage. It appraises against comparable sales. It conveys with the deed. Same closing as any other house.
Two houses can look identical from the road and be completely different transactions. That's not a technicality. It's the whole deal.
Mississippi has two paths, and they're not the same
Here's the part almost nobody gets right, including some people who should.
The first path is tax classification. Under Section 27-53-15, an owner who owns the land can elect to have the home classified as real property for ad valorem tax purposes only. To do it, the wheels and axles have to come off and the home has to be anchored and blocked according to rules set by Mississippi's Commissioner of Insurance. The county tax assessor issues a certificate, charges a fee, and files it in the land records.
Read that phrase again. For ad valorem tax purposes only. Your tax bill changes. Your legal classification for financing does not.
The second path is title retirement under Section 63-21-30. The certificate of title goes to the state for cancellation, and an affidavit of affixation gets recorded in the land records of the county. Once that affidavit is filed, the statute says the home is considered real property for ad valorem taxation and for all other purposes.
Those last five words are the ones that matter. All other purposes. That's what a lender needs to see.
So when a listing says a manufactured home is "on a permanent foundation and taxed as real property," that may be true and still not be enough. Pull the land records and confirm the affidavit of affixation is actually recorded. If it isn't, the title was never retired, and your buyer's financing may not exist.
June 15, 1976 is a wall
That's the day HUD's construction and safety standards took effect. Homes built on or after it are manufactured homes. Homes built before it are mobile homes, and for financing purposes they're a dead end.
Pre-1976 homes are ineligible for FHA, VA, USDA, Fannie Mae, and Freddie Mac financing regardless of condition. It doesn't matter how nice the renovation is. No lender can override it. Those sales happen for cash or through portfolio lenders, which shrinks your buyer pool dramatically.
Proof of build date comes from the HUD certification label, a red tag on the exterior of each section, and the data plate inside, often near the electrical panel or in a kitchen cabinet. Missing labels are common on older units, and a missing data plate makes lenders nervous. Verification is available through IBTS or the manufacturer, but it's another step and another delay.
Check for the tag before you get attached to the property. It takes two minutes.
The foundation certification
FHA and VA both require the home to sit on a permanent foundation meeting HUD standards, certified by a licensed structural engineer. Hitch, axles, and wheels removed. Proper footings and anchoring. A permanently enclosed crawl space with adequate clearance. Utilities permanently connected.
If a certification already exists, get a copy. If it doesn't, budget roughly $400 to $700 for an engineer to inspect and certify, and build the time into your contract period.
There's also a moving problem. VA generally allows one move, but many lender overlays decline homes relocated after original installation, and Fannie and Freddie require the home to have never moved from its original site. If a home has been moved twice, ask about financing before anything else.
Size minimums apply too. VA requires at least 400 square feet for a single-wide and 700 for a double-wide.
What this does to your loan
When everything lines up, meaning post-1976 build, permanent foundation, title retired, land owned, the financing looks close to normal. FHA, VA, and USDA all work. Conventional programs like Fannie Mae's MH Advantage and Freddie Mac's CHOICEHome exist specifically for qualifying manufactured homes and price much closer to site-built terms.
When something doesn't line up, you're looking at a chattel loan, a portfolio lender, or cash. Rates are higher, terms are shorter, and the pool of buyers who can pay for it is a fraction of the size.
Talk to a lender before you write, not after. And if you're a veteran, note that a manufactured home has to clear both VA requirements and state classification rules, which is a different conversation than a standard VA purchase. The down payment picture also shifts depending on which program you land in.
Insurance, wind, and flood down here
This is where the Coast adds its own layer.
Carrier appetite for manufactured homes is narrower than for site-built, and that's before you factor in being on the Gulf. Don't assume the premium you'd pay on a stick-built house of the same value applies. Quote the specific address with the specific home before you write an offer, and ask the agent directly whether they can write manufactured housing at all.
Wind is the first question. Remember that the wind pool covers six whole counties, and that wind and hail coverage is usually inside the base homeowners policy on the Coast though some carriers exclude it. Our post on what insurance costs here is a starting point, not an answer for this property type.
Flood is the second. Manufactured homes have their own rating treatment under the NFIP, and elevation and anchoring requirements in mapped flood zones are strict. If the property is in a special flood hazard area, get the elevation certificate question answered early. And if you're looking anywhere near the water, understand that coastal high hazard zones limit what can be placed there at all.
There's a nice bit of Mississippi trivia buried in the statute worth knowing: the anchoring and blocking rules for classifying a manufactured home as real property are promulgated by the Commissioner of Insurance, not by a building department. That tells you how the state thinks about these homes.
What it does to resale
Land holds value. The structure generally doesn't appreciate the way a site-built house does, so on a manufactured home on acreage, a lot of your equity story is the dirt.
That's not a knock. Plenty of good buys north of I-10 are exactly this, and in places like Vancleave or Saucier, a manufactured home on a few acres gets people into ownership at a number a site-built house on the same land wouldn't touch.
What hurts resale is paperwork, not the house. A home with a retired title, a recorded affidavit of affixation, a current foundation certification, and readable HUD tags sells to anybody with a mortgage. The same home without that folder sells to cash buyers and portfolio borrowers only, and a thin buyer pool is one of the surest things that makes a Coast home harder to sell.
If you own one and you're thinking about selling in the next few years, getting the title retired and the foundation certified now is probably the highest-return thing you can do to the property. Cheaper than a kitchen and worth more at the closing table. While you're at it, confirm your homestead exemption is filed correctly, since classification affects how the county carries it.
By the Numbers
June 15, 1976 HUD Code effective date; homes built before it are ineligible for FHA, VA, USDA, Fannie, and Freddie financing
2 separate Mississippi paths to "real property," only one of which counts for all purposes
63-21-30 Mississippi Code section governing permanent title retirement
27-53-15 Mississippi Code section governing classification for ad valorem tax purposes
$10 statutory county tax assessor fee for issuing a classification certificate, plus the chancery clerk filing fee
400 sq ft VA minimum living space for a single-wide
700 sq ft VA minimum living space for a double-wide
$400 to $700 typical cost of an engineer's permanent foundation certification
15 to 20 years typical chattel loan term when the home stays personal property
1 number of moves VA generally allows, though lender overlays are often stricter
0 Fannie and Freddie tolerance for a home moved from its original installation site
The Bottom Line
A manufactured home on owned land is a legitimate way to own property on this coast, especially north of the interstate where land is the point. I've helped people into good situations this way.
But the paperwork is the property. Before you write an offer, confirm three things: the build date from the HUD tag, whether the title has actually been retired with a recorded affidavit of affixation, and whether a foundation certification exists. If all three check out, you're buying a house. If any of them don't, you're buying something the bank may not recognize as a house, and you need to know that going in.
If you own one and want to know where you stand, start with a home value estimate and take a look at the selling process. If you're shopping, our buyer's guide covers the timeline, and a local agent can pull the land records and tell you in an afternoon which kind of property you're actually looking at.
Frequently Asked Questions
Is a manufactured home real property in Mississippi?
Not by default. Under Miss. Code Section 27-53-15, manufactured and mobile homes are personal property unless the owner, who also owns the land, either elects classification as real property for ad valorem tax purposes or permanently retires the title under Section 63-21-30. Only title retirement with a recorded affidavit of affixation makes the home real property for all purposes.
What's the difference between tax classification and title retirement?
Tax classification under Section 27-53-15 changes how the county assesses the home for property tax and requires the wheels and axles removed and the home anchored per rules set by Mississippi's Commissioner of Insurance. Title retirement under Section 63-21-30 cancels the certificate of title and records an affidavit of affixation in the land records, after which the home is real property for ad valorem taxation and all other purposes. Lenders generally need the second.
Can I get a mortgage on a mobile home built before 1976?
Not through FHA, VA, USDA, Fannie Mae, or Freddie Mac. June 15, 1976 is the HUD Code effective date, and homes built before it are permanently ineligible for those programs regardless of condition or upgrades. Financing generally means cash or a portfolio lender.
What is a permanent foundation certification and do I need one?
It's an inspection and certification by a licensed structural engineer confirming the foundation meets HUD standards, including removal of the hitch, axles, and wheels, proper footings and anchoring, and a permanently enclosed crawl space. FHA and VA both require it on manufactured homes. If one doesn't exist, expect roughly $400 to $700 and additional time.
Does it matter if the home has been moved?
Yes. VA generally allows one move, but many lender overlays decline homes relocated after original installation. Fannie Mae and Freddie Mac require that the home never moved from its original installation site. Confirm the history before assuming financing is available.
How do I verify the build date?
Look for the HUD certification label, a red tag on the exterior of each section, and the data plate inside, often near the electrical panel or inside a kitchen cabinet. If labels are missing, verification is available through IBTS or the original manufacturer, though it adds time to the transaction.
Is a manufactured home harder to insure on the Mississippi Gulf Coast?
Carrier appetite for manufactured housing is narrower than for site-built homes, and coastal exposure narrows it further. Confirm that a carrier will write the specific home at the specific address before writing an offer, and treat wind and flood as separate questions from the base policy.
Sources
Miss. Code Ann. Section 27-53-15, classification of manufactured and mobile homes: https://law.justia.com/codes/mississippi/title-27/chapter-53/section-27-53-15/
Miss. Code Ann. Section 63-21-30, cancellation of certificate of title for a manufactured home classified as real property: https://law.justia.com/codes/mississippi/2013/title-63/chapter-21/section-63-21-30/
HUD, Manufactured Home Certification Label and Data Plate information: https://www.hud.gov/program_offices/housing/rmra/mhs/faqs
HUD, Permanent Foundations Guide for Manufactured Housing: https://www.huduser.gov/portal/publications/permfound.html
VA Loan Network, VA loans for manufactured and mobile homes, May 2026: https://valoannetwork.com/va-loans/va-loans-for-manufactured-and-mobile-home/
Manufactured Nationwide, VA manufactured home requirements, July 2026: https://www.manufacturednationwide.com/va-standards-for-manufactured-homes
RefiGuide, manufactured home loan programs and requirements, 2026: https://www.refiguide.org/manufactured-home-loans/
Mississippi Department of Revenue, title and registration: https://www.dor.ms.gov/
FEMA, NFIP flood insurance and manufactured housing requirements: https://www.fema.gov/flood-insurance
Randy Richardson is a Broker Associate and Team Leader of The 4th Right Team at CENTURY 21 J. Carter & Company. He works with buyers and sellers across the Mississippi Gulf Coast, from Bay St. Louis to Pascagoula and north of I-10.
Randy Richardson | Broker Associate
The 4th Right Team | Century 21 J. Carter & Company
Office: (228) 731-3881 | Cell: (228) 547-9999
realtorrandyrichardson@gmail.com
www.The4thRightTeam.com